 Sign up with Google
 Sign in with Zoho
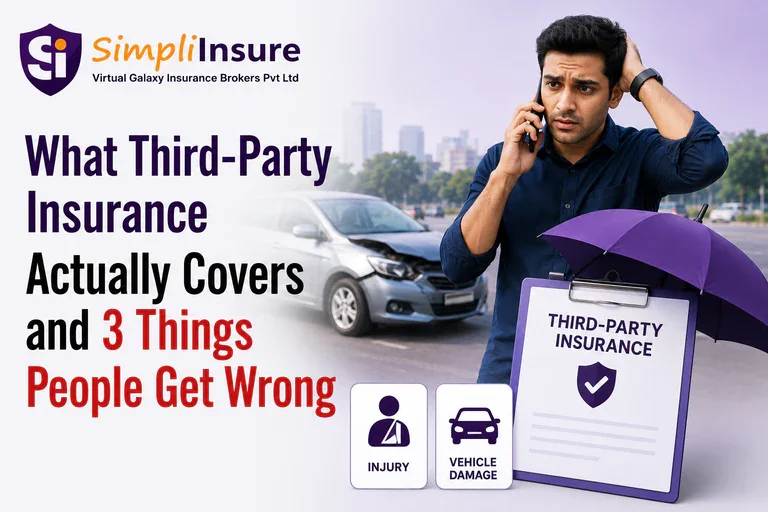
Ramesh, 25, has just bought his first used car at an attractive price. His car already had third-party insurance from the previous owner. Wanting to keep his costs low, Ramesh decides not to buy any additional cover for his car.
A few months later, Ramesh gets involved in a road accident. Another person is injured, while Ramesh's car is also damaged. His passengers also need medical attention.
Ramesh assumes his insurance will take care of everything. But this is where three common misconceptions about third-party insurance can cost a car owner money.
What is Third-Party Insurance?
Third-party insurance protects the vehicle owner against covered legal liability arising from injury, death, or property damage caused to a third party by the insured vehicle.
Think of a situation where you break your neighbour's window. It makes you liable for the damage caused to another person, the third party. Your insurer will protect you against the covered liability for the loss of the window that you caused.
Misconception 1: "Third-Party Insurance Covers My Car Damage and My Passengers"
Against popular assumptions, third-party insurance does not cover damages caused to the policyholder’s own car, injuries caused to themselves due to the accident, or injuries caused to any passengers present in the insured vehicle.
For the accident caused by Ramesh, only the bodily injury to the third party or any vehicle damage caused to their vehicle is covered by this third-party insurance.
These added liabilities arising from the road accident can be covered only through other forms of insurance. Damages to Ramesh’s insured car can be covered by the Own-Damage cover provided in car insurance policies. An Owner-driver Personal Accident cover can cover injuries to Ramesh. Injuries to the passengers can be covered by their individual Personal Accident covers or a Group Personal Accident cover
So now, with only third-party insurance, Ramesh would have to spend ₹75,000 as the repair bill of his own car, and ₹25,000 for treating his own injuries from the accident. The injured passengers may present Ramesh, the legally liable party, with a motor accident compensation claim before the Motor Accidents Claims Tribunal (MACT), as per Section 166 of the Motor Vehicles Act, 1988.
Misconception 2: "Third-party Insurance Will Pay the Person Owed Fully"
Many new car owners like Ramesh may assume that all the third-party damages will be covered by their third-party insurance. That may not be true in all cases.
For insurance purposes, the damages caused can be categorized into third-party property damage (TPPD) and third-party bodily injury or death. There are limits on the insurance payouts that can be claimed based on the damage type.
For property damage, there is a statutory minimum liability of ₹6,000 under Section 147(2)(b) of the Motor Vehicles Act, 1988. The cap has been extended to ₹7.50 lakhs for private cars and commercial vehicles by Government Regulation No. 39 of the Indian Motor Tariff 2021.
For bodily injury or death, there is no cap on the insurance payout. Section 147(2)(a) of the Motor Vehicles Act, 1988, states the limit to be “the amount of liability incurred”.
Also, car insurance plans will often have deductibles, applicable per claim, that would further impact the insurance payout amount.
If Ramesh causes property damage of ₹12 lakh and bodily injury of ₹35,000, then he still has to pay the remaining ₹4.5 lakh for damaging the vehicle of the third party. Ramesh’s insurance company may cover treatment for the injuries of the third party. With applicable deductibles of ₹1,000 for each claim, Ramesh would ultimately pay ₹4.51 lakh for the vehicle damage and ₹1,000 towards treatment of the third party.
No third-party insurance cover for driving drunk or without a licence:
If Ramesh had caused that accident while driving intoxicated or without a valid car licence, the insurer would have a duty to compensate the third-party victim, but also gain the right to recover damages from Ramesh. Even with an own-damage cover, his insurance claim would be denied, and he would end up paying ₹12.35 lakh for all the damages.
Ramesh’s Legal Liability (LL) enforces damage cover through his personal wealth, with lasting financial implications:
Legal Liability means that since Ramesh caused the accident, he became responsible for all the damages incurred by the third-party victim. So if his insurance is unable to cover the entire damage, including bodily injury or possible damages to the victim’s vehicle, then Ramesh is legally liable to pay for the rest of the damages. The liability may also involve interest and litigation-related costs, depending on the proceedings and orders passed.
Now, Ramesh having a low-premium third-party insurance will lead to difficult consequences, even beyond astronomical expenses. If the court finds that Ramesh is unable to pay the ₹4.51 lakh compensation through his liquid assets, then the legal system provides mechanisms to recover it.
The Motor Accident Claims Tribunal (MACT) can issue a certificate to the Collector, who can recover the outstanding damages in the same manner as an arrear of land revenue from Ramesh, according to Section 174 of the Motor Vehicles Act, 1988. That leads to the actual provision, which details what eligible physical assets may be attached for recovery under Section 60 of the Code of Civil Procedure, 1908, and it includes land, houses/buildings, goods, money, securities and other saleable movable or immovable property, subject to statutory exemptions. This kind of MACT award was granted in the Gurvinder Singh vs Ramla Devi And Ors on 20 August, 2024 judgment. Due payable amounts may also be recovered through the attachment of salary, as stated in Section 60 of the Code of Civil Procedure, 1908. This method of recovery was used in the case of Ranjit Singh vs New India Assurance Comp. on 8 January, 2016.
Such recovery proceedings can place significant pressure on the person's finances and assets of anyone like Ramesh.
Misconception 3: "Third-Party Insurance Is Optional, I will Renew it Later"
Third-party insurance is not an optional add-on if Ramesh wants to use his car on public roads. It is spelt out in Section 146(1) of the Motor Vehicles Act, 1988.
This legal requirement has been put in place so that the innocent victim of such accidents is not left without compensation for the damages they incur.
If Ramesh had forgotten to renew the third-party insurance on his car and then gotten into this accident, in this case he would also be liable to pay the full damage caused to the victim, equaling ₹12.35 lakh.
Why SimpliInsure?
New car owners may miss many of the features of their third-party insurance, which can cost them money.
1. Ramesh had a misconception that his existing third-party insurance would cover damages to his car and injuries to him and his passengers.
SimpliInsure’s advisors would have informed Ramesh of insurance that covers other accident-related damages like his car repairs, or treatment of injuries he and his passengers sustained. Buying insurance for these would later save Ramesh from undue spending after another car accident.
SimpliInsure’s platform lists coverage details of various car insurance policies, coupled with buying guidance provided by our advisors, a combination that would help Ramesh choose the best-fit policy.
2. Ramesh had a misconception that his third-party insurance would pay for the entire damage to the third-party victim.
SimpliInsure’s advisors would have shown the limits and exclusions on third-party payouts, with details on the difficult implications of Legal Liability if his cover falls short of the damages, so that Ramesh could financially plan for such extra expenses and protect himself from long-lasting legal implications.
3. Ramesh had a misconception that his third-party insurance could be renewed at his convenience.
SimpliInsure’s advisors would have clarified the statutory mandate of always having third-party car insurance in India. That would save Ramesh from unwanted expenses that could have been paid with a valid existing insurance policy.
Our car insurance experts would point out to Ramesh the necessity of having all the accident-related covers such as own-damage, legal liabilities, and passenger cover.
SimpliInsure exists to protect you from a liability like Ramesh’s ₹12.35 lakh by ensuring you have the right cover before an accident happens, and you are not left alone to understand your sudden liabilities when it’s too late.
What Next?
Ramesh's financial burden came entirely from what his third-party insurance never covered: his own car, his own injuries, and his passengers. Own-Damage cover and Owner-driver Personal Accident cover would have closed that gap for him.
The question now remains whether you want to choose this necessary cover before an accident, or whether you want to suffer after one.
Here's how to get covered in 5 simple steps:
1. Start at the SimpliInsure platform.
2. For old car owners, enter your car’s license plate number. For new car owners, enter these details – brand, model, fuel type, manufacture & registration date, colour, Chassis & Engine, cubic capacity, variant, and city or RTO.
3. Select the type of policy – Comprehensive or Standalone Third-party (TP).
4. Answer this – “Do you have a previous policy?” If yes, enter these policy details – policy type, expiry date, NCB, Insurer, and policy number.
5. Your dashboard will display all applicable policies, with details on insurer, tenure, policy type, covers, and add-ons available. You can also include extra add-ons, covers, and discounts for your vehicle.
SimplInsure’s advisory team will guide you through all questions you may have on car insurance. Just call us on +91 95133 55661 and get your car insurance-related queries resolved in 30 minutes.
Get complete car insurance coverage today and save yourself from future financial accidents.
Disclaimer: This content is for informational purposes only and should not be treated as financial, medical, or insurance advice. Policy terms, exclusions, and benefits vary across insurers. Please review official policy documents and seek professional guidance before making decisions.
.webp)