 Sign up with Google
 Sign in with Zoho
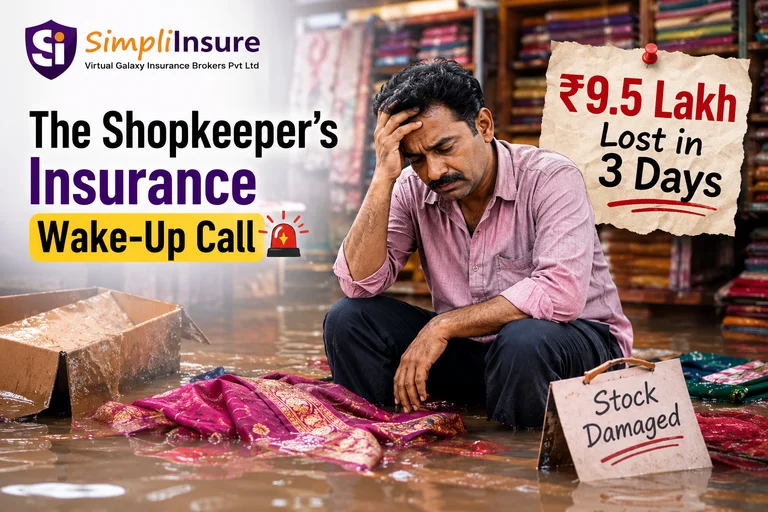
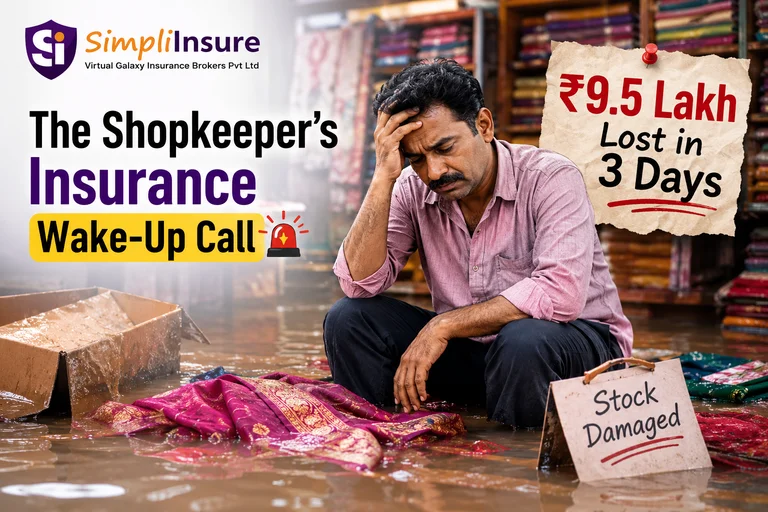
Punith has run his saree retail shop in Malleswaram, Bangalore, for over 10 years and has built a successful business with many regular customers. Then one monsoon season cost him ₹9.5 lakh.
Previously, Punith has dealt with slow-sale months, supplier-payment pressures, delayed payments, shop rent increases, small thefts, minor water leaks, and shop repairs, to name a few. He has always been able to handle these sudden monetary demands. Savings would sometimes cover the losses, or suppliers would give him extra time during cash shortages, and in that way he was able to keep his business.
Regarding insurance, he knew other shop owners in the neighbourhood who were disappointed after making insurance claims and had to shoulder the unexpected financial burden themselves. So Punith never felt that insurance was a reliable necessity for him.
This year, though, a particularly severe spell of rain caused flooding in Malleshwaram. Water entered Punith’s ground-floor shop and damaged a large part of his saree stock along with other equipment. His total loss was not trivial; it equalled ₹9.5 lakh.
What Punith did not know was that there were insurance policies built for shopkeepers like him, to protect against the exact loss that he suffered.
Why do I need Shopkeepers Insurance?
A Shopkeeper’s Insurance policy is designed to protect a shop and its insured contents from covered events, such as flooding, fire, and more. These events may be rare, but when they occur, they leave an unmanageable impact on the finances of a business.
These are specialized packaged policies, which covers fire, burglary, theft of stock and cash, damage to electronic equipment, and any public liability caused. The actual coverage will change with the policy and insurer.
In the last 10 years, Punith had already managed several financial burdens and losses, as they would always be within the range of ₹1.5 lakh. But a ₹9.5 lakh loss was different. It would require him to cut into a large part of his savings and emergency funds, or borrow money from his family or the bank.
That is why having a shopkeepers’ insurance matters. It helps transfer this sudden heavy risk from the shop owner to an insurer, so that people like Punith can safely come out of catastrophic setbacks.
Misconception 1: "My savings, chit fund and supplier credit can absorb any major loss"
Punith feels his safety net, which has always taken care of his financial burdens, might work again in this current predicament.
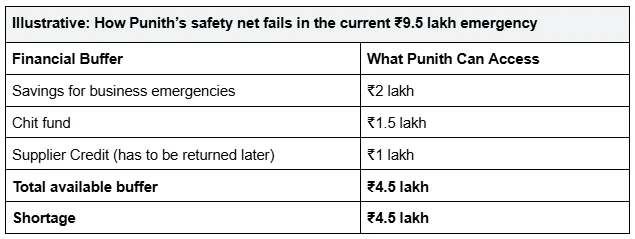
Punith uses his entire emergency savings of ₹2 lakh towards rebuilding his business. But if that money was also used for rent, employee salaries, or other emergencies related to health or property, then there is none left now.
The supplier credit that he was able to negotiate will also have to be returned later. This part of the buffer just created a future obligation of ₹1 lakh, and it just delayed the risk instead of transferring it away.
The complete financial impact may be even bigger than the visible loss of ₹9.5 lakh. While Punith’s business is being restored, he will face a revenue shortage with continuing obligations to pay rent, employee salaries, utility bills, and supplier needs, which total ₹1.8 lakh each month. His saree business was earning about ₹4 lakh in sales each month. Now, he has a deficit of ₹2.2 lakh, which keeps adding up with each month of shop closure. This is the cash-flow shock on top of physical loss. He has already depleted his emergency savings, but these payments have to be met from somewhere.
So at this point, Punith is short by ₹4.5 lakh to cover the direct damages to his business, and he needs another ₹2.2 lakh for monthly payments with each passing month. He also has to pay back the ₹1 lakh credit he received. To compensate for this growing gap, Punith will have to either take a short-term business loan, liquidate personal investments, or borrow from family.
Many banks, including SBI, offer business loans starting from ₹10 lakh up to ₹50 lakh. But this loan has to be paid back with interest. Punith ends up creating another future monetary obligation through this loan. And this obligation may continue even while his revenue may be stalling.
Misconception 2: "My inventory is not going anywhere. Paying a Premium feels like a Waste"
Punith has managed his saree inventory very well in the last 10 years; he kept them all stored in protective packaging and elevated from the storage floor. With such good care, his inventory remained safe for years, and he felt it unnecessary to spend money on insurance that would never come back to him.
But now, when the flood happened, water rose beyond the levels he had planned for, and his inventory got damaged in a day despite his years of precautions.
If Punith had instead bought a shopkeepers insurance plan, like the Fire & Burglary policy from Tata AIG, then to cover his damages of ₹9.5 lakh (₹8 lakh of stock and ₹1.5 lakh of shop contents), the quoted tax-inclusive premium would equal ₹3077 per year or ₹256 per month (Tata AIG premium calculator was accessed in August, 2026).
By avoiding this certain cost of ₹256 every month, or ₹30,770 over 10 years, Punith essentially retained the catastrophic risk of ₹9.5 lakh.
Misconception 3: "Even if I buy insurance, the insurer will reject my claim"
Punith was making the mistake of assuming all claims get rejected.
The insurance claim payouts are subject to the policy’s coverage, exclusions, deductibles, and claim settlement terms. If flooding is covered as a peril, the affected contents and stock are insured for the correct amounts, and he meets policy conditions, then he has a basis for a claim. The insurer will assess the damage and pay the amount admissible under the policy.
If Punith had bought insurance that covered the flood peril, insured his stock for the right amount, and met the claim conditions, then the insurer would assess the damages and pay. By assuming the worst, he is retaining the ₹9.5 lakh financial shock all for himself.
Why SimpliInsure?
Business owners like Punith often struggle to visualize the benefits of a Shopkeepers Insurance policy, because they feel they are paying premiums for something that may never happen.
1. Punith held the misconception that his personal financial safety net would absorb the losses to his business from disasters like a flood, including catastrophic ones.
SimpliInsure’s advisors would help calculate the safety net that he would require based on his business valuation, so that he gets the complete picture of how much his existing safety net falls short, and which policy would cover his business the best.
2. Punith held the misconception that insurance is a waste of money for his saree products that don’t go stale.
SimpliInsure’s advisors would have shown him clearly the trade-off he was unknowingly taking: the cost of a premium (₹256/month) versus the scale of damage (₹9.5 lakh).
With this clarity, they would also help him choose the best policy with suitable premiums and applicable deductibles and co-payments, so that it does not feel like he is wasting money.
3. Punith held the misconception that shop damage insurance claims are never accepted.
SimpliInsure’s advisors would inform him about the plan coverage, exclusions, and claim settlement terms before he buys one. That way, he can adequately ensure his claims are met when he needs them.
Ultimately, insurance was not a waste for Punith’s business. The real waste turned out to be his assumption that the ₹9.5 lakh loss would not happen to him.
What Next?
Traditional safety nets for business are very important. But the question to ask is: Do you want to be adequately covered with insurance as further support?
Don’t wait for a disaster to find out if your business has an adequate safety net.
Call SimpliInsure on +91 95133 55661 /62 /63 /64, and our advisors will help you assess your shop’s risk exposure and the cover you need.
You can check the policies available on the SimpliInsure platform, and our advisory team will present the best policy options and explain the coverage, exclusions, and claim conditions in plain language, so that you do not feel guilty after signing one.
No guesswork. No surprises about what your policy covers. Just clarity before you commit.
Disclaimer: This content is for informational purposes only and should not be treated as financial, medical, or insurance advice. Policy terms, exclusions, and benefits vary across insurers. Please review official policy documents and seek professional guidance before making decisions.