 Sign up with Google
 Sign in with Zoho
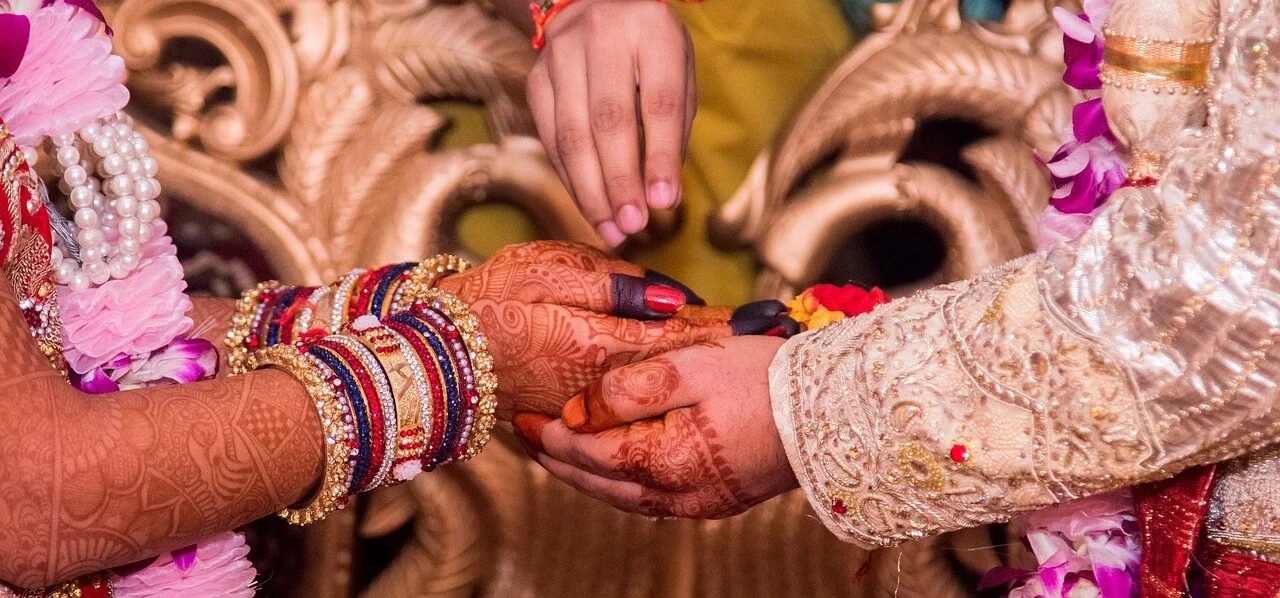
Weddings can feel like one of the happiest days of a person’s life. Yet the bill can be hard to ignore. Between the venue, food, clothing, and decor, costs add up fast. For many couples, a marriage loan is a practical way to spread out those costs. This piece looks at common loan choices for wedding spending and explains the usual steps for getting a personal loan.
Understanding Marriage Loans
What is a Marriage Loan?
A marriage loan is money borrowed to pay for wedding related expenses. It is meant for couples who want to hold the event but do not want to face the full cost right away. In many cases, these loans fall under personal loans. That setup can help with repayment options, including different terms and loan sizes.
Why Look at a Marriage Loan?
Weddings can cost a lot more than people expect. The price can be a few thousand dollars or it can go into the tens of thousands. A marriage loan gives a couple the money right away. That can help them plan the day and stay on track with the budget. It also helps avoid having to put parts of the wedding off or cut things that feel important. Some lenders also list fair rates on personal loans, so it can be a practical choice.
Loan Options for Wedding Costs
1. Personal Loans
Personal loans are one of the usual ways to pay for a wedding. They are unsecured, so you do not need to pledge collateral. Because of that, the borrower is not putting personal items at risk. The process often starts with a review of credit history. Then the lender decides how much to offer based on income. After that, both sides agree on a repayment schedule. One key benefit is that the money can be used for many wedding related expenses, not just one category.
2. Loans meant for weddings
Some lenders have loans that are designed for wedding spending. The payback schedule can be set up to fit the situation. Rates may be fair, and the loan can be used for costs like the venue deposit, catering, and the photographer. Even so, do not rush. Check the full agreement so you can spot extra charges and any rules that apply.
3. Credit cards
Another way to pay for a wedding is a credit card. Some couples do this to spread payments out and keep money available for other bills. They may also get rewards. Still, this option can backfire if the balance is not controlled. Credit card interest can be steep, and debt can grow fast if you miss payments or pay only the minimum. It also helps to keep your spending portion low, around 30 percent, so your credit score stays in better shape.
Picking the Right Loan for Your Wedding
Look at Your Spending First
Before you choose a loan for your wedding, check what you can truly afford. List your expected expenses in clear groups, such as the hall, food, outfits, and music or other activities. Once you see the full total, you can estimate the amount you should borrow. This also helps you avoid taking more than you need.
Shop Lenders and Rates
Interest rates are not the same across lenders. Take time to compare offers instead of grabbing the first one you find. Many people use online tools to see which rates look best for wedding loans or personal loans. Even a small rate change can matter a lot when the loan is repaid over months or years.
Read the Fee Details
Do not rely only on the interest rate numbers. Ask each lender about processing costs, any fee for paying early, and any extra charges that might be added later. Some offers look good at first, but the extra fees can raise the real cost.
Review Your Credit Record
Lenders often look at your credit score during the loan review. A stronger score can lead to friendlier rates and better payment terms. Couples should check their credit report ahead of time and fix any mistakes they notice before applying.
Personal Loan Process
Step 1: Look at Lenders and Compare
First, check several lenders. Compare their rates, extra charges, and repayment terms. A lot of lenders let you apply online, so it is easier to send your details and get quotes.
Step 2: Collect Your Papers
Get the documents you will need. This can include proof of income, tax forms, and a form of ID. If you have them ready, the application usually goes faster.
Step 3: Fill Out the Application
After you pick a lender, complete the application. The lender will review your credit and look at your past financial work to decide if you qualify.
Step 4: Check the Offers
If your request is approved, the lender will share offer options. Read each option closely. Focus on the interest rate, how much you can borrow, the payback schedule, and any fees.
Step 5: Choose One and Confirm
When you decide on an offer, follow the lender’s steps to accept it. You may need to sign forms online or sign in person.
Step 6: Get the Money
Once you accept the loan, the lender sends the funds. This often happens within a few days, so you can cover the wedding costs as planned.
Conclusion
Managing wedding expenses can be difficult, but marriage loans provide a practical financial solution for many couples. By understanding the different loan options available and following the personal loan procedure, couples can find the right financing to celebrate their special day without unnecessary financial strain.
Before proceeding, couples should carefully evaluate their budget, compare different lenders, and fully understand the terms of any loan they are considering. Doing so can lead to a memorable wedding experience without the weight of financial burdens overshadowing their celebration.