 Sign up with Google
 Sign in with Zoho
Market Overview:
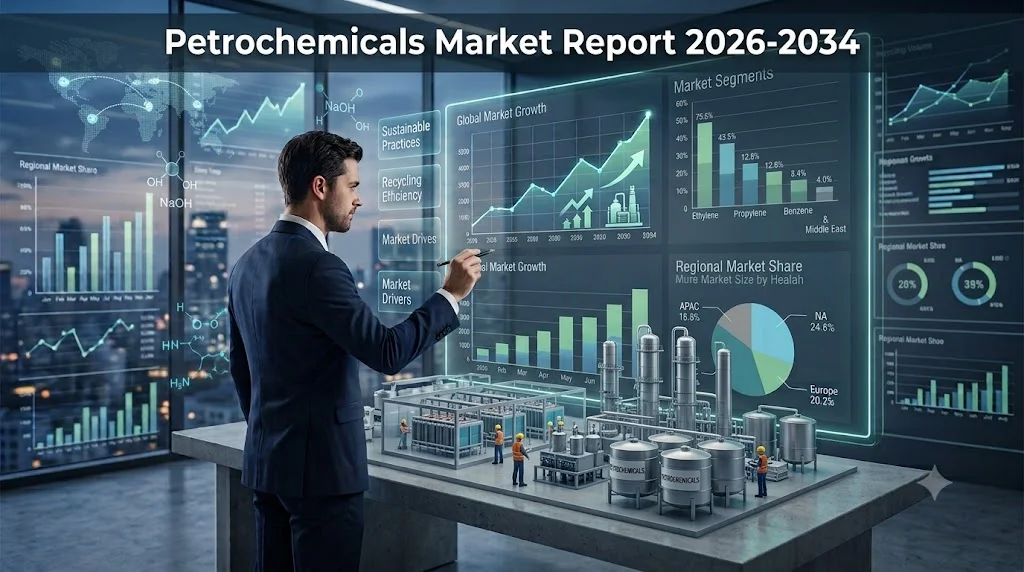
According to IMARC Group’s latest research publication, “Petrochemicals Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034”, The global petrochemicals market grew from USD 675.7 Billion in 2025 to USD 705.5 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 996.1 Billion by 2034, exhibiting a growth rate (CAGR) of 4.40% during 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
How AI is Reshaping the Future of the Petrochemicals Market
- AI-driven predictive analytics are being deployed across petrochemical plants to optimize crude oil feedstock utilization, helping reduce production inefficiencies by up to 12% through real-time process monitoring and smart refining adjustments.
- Government initiatives such as India’s National Green Hydrogen Mission and the US Inflation Reduction Act are channeling billions in funding toward cleaner petrochemical feedstock alternatives, incentivizing companies to explore AI-led emissions tracking and green chemistry models.
- Companies like Sumitomo Chemical are using AI-guided process modeling to develop green propylene production from ethanol, with a pilot plant built under Japan’s Green Innovation Fund and targeting commercial-scale output to reduce fossil-based propylene dependency.
- AI is enabling bio-based polymer innovation at scale, with global bioplastic production reaching an estimated 2.2 million tons and projected to exceed 7.4 million tons as machine learning accelerates the development of new bio-derived polymer formulations across packaging and healthcare applications.
- Supply chain risk management in the petrochemicals sector is being enhanced by AI tools that monitor OPEC output decisions, geopolitical disruptions, and feedstock price swings in real time, enabling companies to implement hedging strategies and reduce exposure to crude oil price volatility.
Key Trends in the Petrochemicals Market
- Crude Oil Price Volatility Reshaping Cost Strategies: Fluctuations in crude oil prices directly impact production costs and profitability across the petrochemical value chain. When crude prices rise, manufacturers face higher feedstock costs, which are often passed down to downstream sectors including packaging, automotive, and construction. In 2022, crude oil was priced at approximately USD 637 per cubic meter, and global producers continue to calibrate output strategies through bodies like OPEC, whose members controlled 72% of proved crude reserves and 37% of production in 2021. Petrochemical companies are increasingly deploying hedging instruments to manage this persistent risk.
- Surging Demand from Packaging, Automotive, and Construction Sectors: Petrochemical-derived plastics account for more than 17% of global petrochemical production, with the packaging sector remaining a primary end user owing to the lightweight, durable, and cost-effective nature of polymer-based materials. In the automotive sector, plastics and synthetic fibers derived from petrochemicals are integral to component manufacturing, while the US market for advanced construction petrochemicals was projected to expand by 32% in near-term estimates. Advanced economies use up to 20 times more plastic than developing countries such as India and Indonesia, signaling an ongoing shift in consumption geography.
- Accelerating Shift Toward Sustainability and Green Chemistry: Environmental regulations and consumer pressure are compelling petrochemical producers to invest in cleaner production technologies and eco-friendly alternatives. Global bioplastic output stood at 2.2 million tons and is projected to reach 7.4 million tons, reflecting a structural shift toward bio-based polymers. The ethylene segment, which leads in global production capacity at 223.86 million metric tons, is witnessing innovation in carbon dioxide conversion technologies, including a copper-catalyst-based method developed by University of Cincinnati researchers to produce ethylene more efficiently from greenhouse gas emissions.
- Polymers Segment Dominating Application Landscape: Global plastic polymer production reached 460 million tons per year and is projected to nearly triple from 2019 levels by 2050. The sheer versatility of polymers, spanning applications from synthetic fibers and rigid plastics to flexible packaging, makes them indispensable across modern manufacturing. Research and development efforts in polymer chemistry are opening new frontiers, including high-performance materials for electrical and electronics applications and medical-grade polymers for healthcare packaging.
- Asia Pacific Emerging as the Growth Engine: The Asia Pacific region accounts for the largest share of the petrochemicals market, supported by rapid urbanization, growing industrial activity, and a surging middle-class population expected to represent two-thirds of the global middle class by 2030. China’s domestic demand for petrochemical feedstocks was significantly higher in 2023 compared to 2019 levels, while India is expanding its refining capacity to meet growing fuel and petrochemical demand driven by rapid economic expansion. Favorable trade policies and foreign direct investment continue to reinforce the region’s strategic position in the global supply chain.
We explore the factors driving the growth of the market, including technological advancements, consumer behaviors, and regulatory changes, along with emerging petrochemicals market trends.
Growth Factors in the Petrochemicals Market
- Industrial Demand Diversification Across End-Use Sectors: The petrochemicals market benefits from broad cross-sector demand spanning packaging, automotive, construction, healthcare, and electrical and electronics. Each sector depends on different petrochemical derivatives, providing the market with a diversified demand base that is resilient to downturns in any single vertical. Packaging alone accounts for more than 17% of global petrochemical production, while the automotive sector continues to increase its use of synthetic fibers and engineering plastics in vehicle manufacturing to reduce weight and improve fuel efficiency.
- Capacity Expansion and Strategic Investments in Infrastructure: Large-scale investment in petrochemical infrastructure is supporting market growth across key regions. The QatarEnergy and Chevron Phillips Chemical Company partnership to build the Ras Laffan Petrochemicals Complex represents a USD 6 billion commitment to expanding global supply capability. Similarly, India’s Hindustan Petroleum Corp planned the launch of its 9 million ton-per-year Barmer refinery and petrochemical project in Rajasthan, reinforcing the country’s ambition to become a larger participant in the global petrochemicals value chain.
- Rising Demand for Ethylene as the Foundation of Downstream Chemistry: Ethylene represents the largest type segment in the market, with a global production capacity of 223.86 million metric tons. As a primary building block for polyethylene, PVC, and a range of industrial solvents, ethylene’s demand is directly linked to the health of its downstream industries. Environmental innovation in ethylene production, such as the development of CO2-to-ethylene conversion using copper catalysts, is both reducing the environmental footprint of production and opening new feedstock pathways beyond crude oil.
- Government-Backed Sustainability Programs Driving R&D Investment: Governments across Asia, Europe, and North America are actively funding green chemistry programs that directly influence petrochemical production models. Japan’s Green Innovation Fund is supporting Sumitomo Chemical’s efforts to commercialize a bio-based propylene production method using ethanol as feedstock. Similarly, the European Union’s sustainability mandates on packaging materials are pushing petrochemical companies to develop certified recyclable and bio-based polymer alternatives that comply with circular economy directives.
- Growing Middle-Class Consumption in Emerging Markets: The expanding middle class in the Asia Pacific, projected to represent two-thirds of the global middle class by 2030, is driving demand for packaged goods, vehicles, consumer electronics, and infrastructure, all of which are significant end markets for petrochemical derivatives. Countries like China and India are not only growing as consumers of petrochemical products but also emerging as major producers and investors in advanced petrochemical manufacturing capabilities.
Leading Companies Operating in the Global Petrochemicals Industry:
- BASF SE
- Chevron Corporation
- China National Petroleum Corporation
- China Petrochemical Corporation
- DuPont de Nemours Inc.
- Exxon Mobil Corporation
- Formosa Plastics Corporation
- Indian Oil Corporation Limited
- INEOS Group Ltd.
- LyondellBasell Industries N.V.
- Reliance Industries Limited
- Saudi Basic Industries Corporation (Saudi Arabian Oil Co.)
- Shell plc
- Sumitomo Chemical Co. Ltd.
- TotalEnergies SE
Petrochemicals Market Report Segmentation:
Breakup by Type:
- Ethylene
- Propylene
- Butadiene
- Benzene
- Toluene
- Xylene
- Methanol
- Others
Ethylene accounts for the largest share on account of its foundational role as a feedstock for a wide range of downstream products including polyethylene, PVC, and industrial chemicals across multiple end-use sectors.
Breakup by Application:
- Polymers
- Paints and Coatings
- Solvents
- Rubber
- Adhesives and Sealants
- Surfactants and Dyes
- Others
Polymers dominate the application segment owing to their exceptional versatility, widespread usage across packaging, construction, automotive, and healthcare industries, and growing innovation in bio-based and sustainable polymer variants.
Breakup by End Use Industry:
- Packaging
- Automotive and Transportation
- Construction
- Electrical and Electronics
- Healthcare
- Others
Breakup by Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
Asia Pacific holds the leading position in the global petrochemicals market, driven by rapid urbanization, expanding industrial activity, a growing middle-class population, and substantial government investments in refining and petrochemical manufacturing infrastructure across China and India.
Recent News and Developments in the Petrochemicals Market
- May 2026: INEOS and Shell entered a partnership on Gulf of America projects, with INEOS acquiring a 21% stake, reinforcing collaboration in upstream and petrochemical feedstock operations. Separately, INEOS backed a USD 1.7 billion low-carbon methanol project in Texas City, signaling a major commitment to cleaner chemical production.
- May 2026: TA’ZIZ signed deals worth USD 28.5 billion to advance UAE chemicals sector growth, positioning the region as a significant hub for global petrochemical capacity expansion and reinforcing the Middle East’s role in the international chemical supply chain.
- April 2025: IndianOil signed a deal for a large-scale petrochemical plant in Odisha, while Aramco and Sinopec announced plans to expand petrochemical production at the Yasref facility in Saudi Arabia, reflecting continued investment momentum across emerging and established petrochemical economies.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: [email protected]
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302