
 Sign up with Google
 Sign in with Zoho
Needing money quickly for a wedding, a medical bill, a home repair, or simply to tide over the gap between one pay cheque and the next is one of the most common financial situations people face. A few years ago, getting a personal loan meant taking time off work, standing in a bank queue, filling out long forms by hand, and waiting days or even weeks for a decision that might still come back as a 'no'. Today, the process looks very different. You can apply for a personal loan online from your phone or laptop, often in under ten minutes, and know your eligibility status almost immediately.
This guide walks you through everything involved in applying for a personal loan online: what the loan actually is, who can get one, what documents you'll need, how the process works step by step, what it costs, and how to avoid the mistakes that trip up a lot of first-time borrowers. The goal is to leave you with a clear, realistic picture of what to expect, so you can apply with confidence rather than guesswork.
What Is a Personal Loan, and Why Apply Online?
A personal loan is an unsecured loan, meaning you don't have to pledge any collateral like property, gold, or a fixed deposit to get one. You borrow a fixed amount, which is paid back over a set period through equal monthly instalments (EMIs) that include both principal and interest. Because there's no collateral involved, the application and verification process is largely about your income, your repayment history, and your ability to service the loan.
Applying online simply means doing this entire process digitally instead of walking into a branch. The lender collects your details, verifies them electronically (through PAN, Aadhaar, bank statements, and credit bureau data), and communicates a decision through the website or app. The underlying loan product hasn't changed — what's changed is the speed and convenience of getting it.
Benefits of Applying for a Personal Loan Online
There are a few clear advantages to choosing the online route over a traditional branch visit, and they're worth understanding before you start.
● Speed: Most online lenders can give you an eligibility decision within minutes, and disbursal, once approved, can happen the same day or within 24–48 hours.
● Convenience: You can apply at 11 p.m. on a Sunday from your couch. There's no need to take leave from work or travel to a branch.
● Minimal paperwork: Instead of carrying physical photocopies, you typically upload scanned or photographed documents directly through the website or app.
● Easy comparison: Online, you can quickly compare interest rates, processing fees, and tenure options across lenders before committing.
● Transparency: A good online application shows you the EMI, interest rate, and total repayment amount upfront, before you accept the offer.
Who Can Apply? Typical Eligibility Criteria
Eligibility criteria vary a little from lender to lender, but most online personal loan providers in India look at a similar set of factors. Knowing these in advance helps you understand where you stand before you apply.
● Age: Usually between 21 and 60 years at the time of application (some lenders extend this up to 65 for salaried applicants with pension income).
● Employment status: Salaried employees of private companies, government bodies, or public sector undertakings, as well as self-employed professionals and business owners, are generally eligible.
● Minimum income: Many lenders set a minimum monthly income threshold, commonly in the range of ₹15,000–₹25,000 for salaried applicants, though this varies by city and lender.
● Work experience: A minimum period of continuous employment (often 6 months to 1 year with the current employer, or 2+ years of total work experience) is commonly required.
● Credit score: A CIBIL score of 700 or above is usually treated as a strong application, though some lenders do consider applicants with lower scores, often at a higher interest rate.
● Bank account: An active savings or salary account is required, since EMIs are typically collected through auto-debit (NACH/ECS mandate).
These are general benchmarks, not fixed rules. If you fall short on one criterion — say, a lower credit score — a steady income and clean repayment history on past loans can still work in your favour.
Documents You'll Need
One of the biggest advantages of applying online is that most lenders now accept digital copies of your documents. Here's what you'll typically be asked to upload:
● Identity proof: PAN card and Aadhaar card (or passport/voter ID as alternatives)
● Address proof: Aadhaar card, utility bill, rent agreement, or passport
● Income proof (salaried): Last 3 months' salary slips and the latest Form 16
● Income proof (self-employed): ITR for the last 2 years and business proof such as GST registration
● Bank statements: Usually the last 3–6 months, showing salary credits and existing obligations
● A passport-sized photograph, in most cases
Many lenders can verify your identity and address through Aadhaar-based e-KYC, which can remove the need to upload separate ID proof altogether. Keeping clear, legible scans of these documents ready before you start the application will save you from having to pause midway to hunt for a file.
It also helps to make sure the name, date of birth, and address on each document match exactly. Small inconsistencies, such as a nickname on one document and a full legal name on another, are a surprisingly common reason online applications get sent back for re-verification, which adds days to what should otherwise be a same-day process.
How to Apply for a Personal Loan Online: Step-by-Step
While the exact screens differ between lenders, the online application process generally follows the same broad sequence.
1. Check your eligibility: Visit the lender's website or app and fill in basic details — your name, mobile number, employment type, and monthly income. This usually generates an instant, indicative eligibility result without affecting your credit score.
2. Choose your loan amount and tenure: Based on your eligibility, you can select how much you want to borrow and over how many months or years you'd like to repay it. The platform will typically show you the resulting EMI in real time so you can adjust the numbers to fit your budget.
3. Complete the application form: Fill in your personal, employment, and banking details. Accuracy matters here — a mismatch between the details you enter and what's on your documents can delay processing.
4. Upload your documents: Submit scanned copies or clear photos of your ID proof, address proof, income proof, and bank statements, or complete e-KYC verification where available.
5. Verification: The lender's system cross-checks your details against credit bureau records and may also carry out a quick phone or video verification call.
6. Loan approval and offer: If approved, you'll receive a formal loan offer stating the sanctioned amount, interest rate, tenure, processing fee, and EMI amount.
7. E-sign the agreement: Review the loan agreement carefully and sign it digitally, typically using an Aadhaar-based e-signature.
8. Disbursal: Once the agreement is signed, the loan amount is transferred directly to your registered bank account — often within hours for pre-approved or straightforward applications.
It's worth noting that the time each step takes can vary quite a bit depending on how complete your documentation is and how quickly you respond to any verification calls or follow-up requests. Applicants who upload clear, complete documents the first time, and who answer verification calls promptly, usually move through the process noticeably faster than those who submit partial information and have to go back and forth with the lender's support team.
Understanding Interest Rates, Fees, and EMIs
Before accepting any loan offer, it's worth understanding exactly what you're paying for and what you're paying back. A few terms come up repeatedly, and it helps to know what each one means.
● Interest rate: This is the cost of borrowing, usually quoted as an annual percentage. It can be fixed (stays the same through the tenure) or sometimes linked to the lender's benchmark rate. It typically depends on your credit score, income, and the lender's internal risk assessment.
● Processing fee: A one-time fee, usually a small percentage of the loan amount, charged at disbursal to cover administrative costs.
● EMI (Equated Monthly Instalment): The fixed monthly amount you pay, covering both principal and interest, until the loan is fully repaid.
● Prepayment or foreclosure charges: Some lenders charge a fee if you repay the loan earlier than the agreed tenure. It's worth checking this before signing, especially if you expect a bonus or windfall that could let you close the loan early.
● Late payment charges: Missing an EMI due date usually triggers a penalty and can also affect your credit score, so it's important to keep your repayment account funded on the due date.
Before you accept an offer, ask for (or read) the complete breakup: the principal, interest rate, tenure, processing fee, and total amount repayable. A loan that looks cheap on EMI alone can turn out to be expensive once fees and tenure are factored in, so comparing the total cost of the loan — not just the monthly instalment — is the more reliable way to judge an offer.
Tips to Improve Your Chances of Approval
A few simple habits can meaningfully improve both your odds of approval and the interest rate you're offered.
● Check your credit report beforehand and correct any errors you spot, since an inaccurate entry can unfairly lower your score.
● Avoid applying to multiple lenders within a short window — each formal application can generate a 'hard inquiry' that may temporarily pull your score down.
● Be honest and consistent with the income and employment details you enter; mismatches with your documents are a common reason for rejection or delay.
● Keep your existing debt obligations (credit cards, other EMIs) manageable relative to your income before applying for a new loan.
● Apply for an amount you genuinely need and can comfortably repay, rather than the maximum you're offered.
Common Mistakes to Avoid
Even with a straightforward online process, a few avoidable mistakes account for most of the friction borrowers run into.
● Not reading the loan agreement fully before e-signing, and later being surprised by a fee or clause.
● Entering a different income or address than what appears on supporting documents.
● Ignoring the total cost of the loan and focusing only on the EMI figure.
● Borrowing more than necessary simply because a higher amount was offered.
● Applying through unverified third-party links or apps rather than the lender's own verified website or app, which can expose personal and financial data to misuse.
A Quick Word on Responsible Borrowing
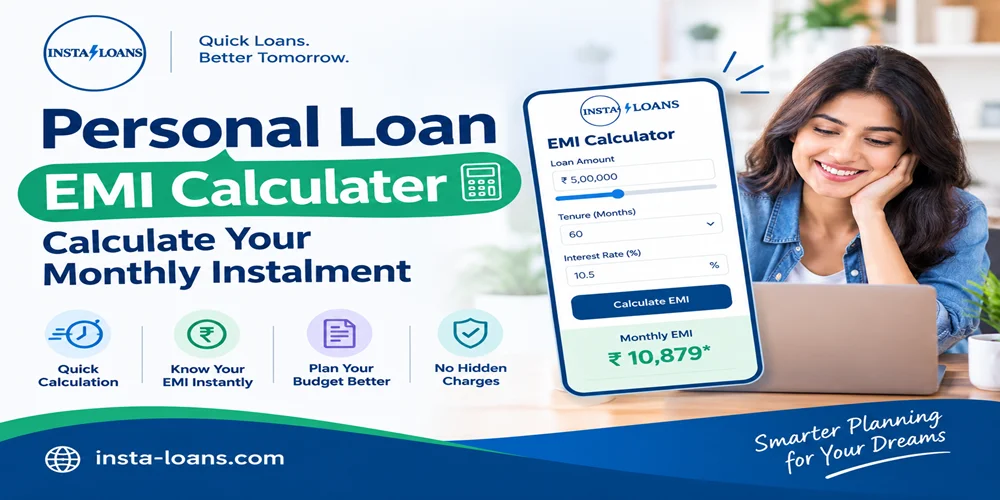
A personal loan can be a genuinely useful tool for managing a one-time expense or consolidating costlier debt, but it is still a financial commitment that needs to fit comfortably within your monthly budget. Before applying, it helps to map out your EMI against your other fixed expenses, keep some margin for unexpected costs, and avoid stacking multiple loans at once. If you're ever unsure whether a loan amount or tenure is right for you, it's worth using an EMI calculator to see the numbers clearly before you commit, rather than after.
Applying with Insta Loans
At Insta Loans, the personal loan application is built to be simple and transparent from start to finish. You can check your eligibility online in a few minutes, compare loan amount and tenure options with a live EMI preview, and complete the entire process — document upload, verification, and e-signing — without visiting a branch. Our aim is to make sure you understand exactly what you're borrowing, what it costs, and what you're committing to, before you accept an offer.
Conclusion
Applying for a personal loan online has made what used to be a slow, paperwork-heavy process considerably faster and more convenient, but convenience shouldn't come at the cost of understanding what you're signing up for. Take a few minutes to check your eligibility, gather your documents, compare the total cost of the offers you receive, and borrow only what you need and can repay comfortably. Done this way, an online personal loan can be a straightforward, practical way to manage a genuine financial need.
Frequently Asked Questions
How long does it take to get a personal loan approved online?
Many online lenders provide an indicative eligibility result within minutes of submitting basic details. Full approval, after document verification, can take anywhere from a few hours to a couple of days, depending on how quickly your documents and bank details are verified. Disbursal usually follows soon after approval.
Can I apply for a personal loan online without a high credit score?
A higher credit score (typically 700 and above) generally improves your chances and can get you a better interest rate, but some lenders do consider applicants with lower scores, often with a higher rate or a lower approved amount. A stable income and a clean recent repayment history can help offset a modest credit score.
What documents are required to apply for a personal loan online?
You'll typically need identity proof (PAN and Aadhaar), address proof, income proof (salary slips and Form 16 for salaried applicants, or ITR for self-employed applicants), and recent bank statements. Many lenders also offer Aadhaar-based e-KYC, which can simplify identity and address verification.
Is it safe to apply for a personal loan online?
It's safe as long as you apply directly through the lender's verified website or official app, check that the site uses secure (HTTPS) connections, and avoid sharing your OTP, PIN, or login credentials with anyone claiming to assist you. Be cautious of unsolicited loan offers through SMS or messaging apps that ask for upfront payments.
What is the minimum salary required to apply for a personal loan online?
This varies by lender and city, but a commonly used benchmark for salaried applicants is a monthly income of around ₹15,000 to ₹25,000. Self-employed applicants are usually assessed on the basis of their business income and IT returns rather than a salary figure.
Can I prepay or foreclose my personal loan early?
Most lenders allow prepayment or foreclosure after a minimum lock-in period, though some charge a prepayment fee calculated as a percentage of the outstanding amount. It's worth checking this clause in the loan agreement before signing, especially if you anticipate being able to repay early.
Will applying for a personal loan online affect my credit score?
A basic eligibility check is usually a 'soft inquiry' and does not affect your credit score. However, once you proceed to a formal loan application, the lender typically runs a 'hard inquiry' with the credit bureau, which can cause a small, temporary dip in your score. Applying to several lenders in quick succession can compound this effect, so it's best to compare offers first and apply formally to one or two lenders you're confident about.


 (1) (3).webp)