Sign up with Google
 Sign in with Zoho
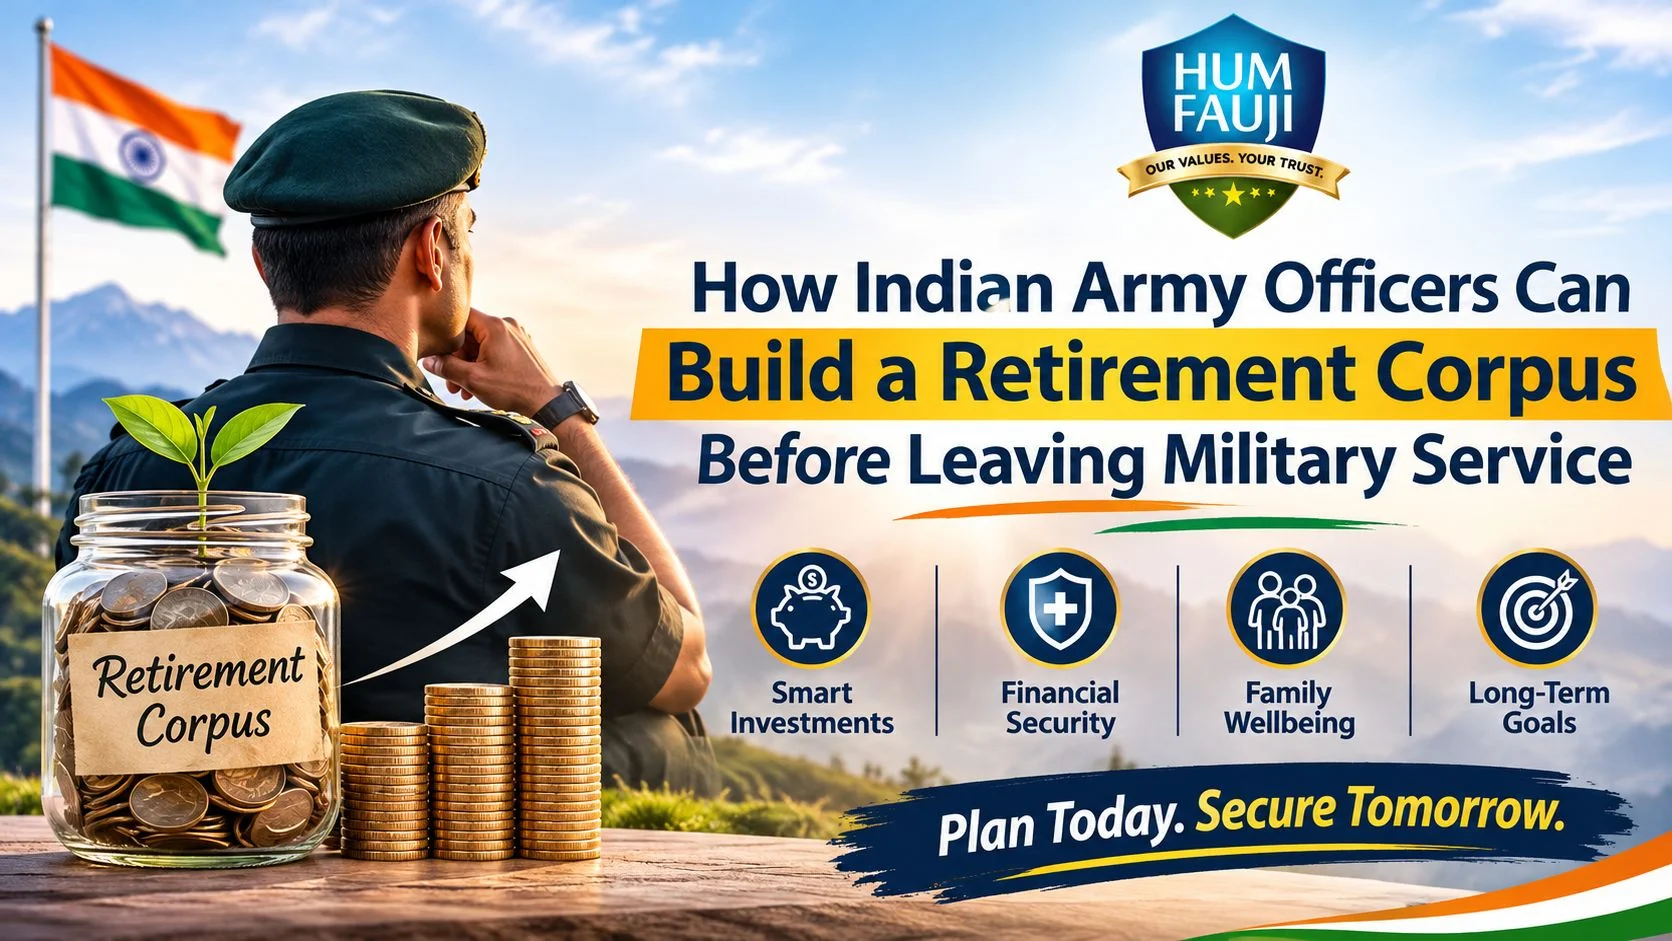
Many officers focus on their responsibilities during service but postpone serious retirement planning until the final few years of their military career. This can create financial pressure, particularly when children’s education, housing expenses, healthcare and post-retirement lifestyle requirements compete for the same resources.
Effective retirement planning indian armed forces officers should begin well before the retirement date. The objective is to build a sufficient retirement corpus that complements pension income and supports financial independence throughout post-service life.
Why Retirement Planning Matters for Indian Army Officers
Military retirement often happens earlier than conventional corporate retirement. Consequently, an officer may need to manage household expenses and financial goals for several decades after leaving service.
Even with pension benefits, several financial responsibilities continue:
- Children's higher education and marriage expenses.
- Purchasing a house or managing existing home loans.
- Healthcare and medical insurance requirements.
- Supporting dependent parents and family members.
- Maintaining lifestyle expenses after retirement.
- Funding a second career, consultancy or business.
Inflation also reduces the purchasing power of money over time. Therefore, retirement planning indian armed forces officers must consider both predictable pension income and investments capable of supporting long-term wealth creation.
Common Retirement Planning Mistakes Army Officers Should Avoid
1. Depending Entirely on Pension
Pension can provide an important foundation for retirement income, but relying exclusively on it may restrict financial flexibility. Additional investments can help address unexpected expenses and changing family requirements.
2. Starting Investments Too Late
Some officers begin serious retirement investments only five years before leaving service. Starting earlier allows investments more time to benefit from compounding and reduces the pressure of making large contributions later.
3. Ignoring Inflation
An amount sufficient for monthly expenses today may not maintain the same purchasing power after 15 or 20 years. Retirement calculations should account for inflation rather than relying on current household expenses.
4. Mixing Retirement Savings With Other Goals
Children's education, property purchases and retirement require separate financial planning. Using retirement investments for short-term expenses can create significant gaps in the future corpus.
Expert Strategies to Build a Retirement Corpus Before Leaving Service
1. Calculate Your Retirement Corpus Requirement
Start by estimating your expected monthly expenses after retirement. Include household costs, healthcare, travel, family responsibilities and lifestyle requirements.
Calculate the future value of these expenses after accounting for inflation. Then consider expected pension income and other predictable cash flows to identify the additional corpus required.
2. Create a Diversified Investment Portfolio
A balanced portfolio can combine different investment categories according to the officer's age, risk tolerance and retirement timeline.
Consider:
- Mutual Funds: Equity-oriented funds may support long-term wealth creation, depending on risk capacity.
- Bonds and Fixed-Income Investments: These can provide stability and predictable cash flows, subject to issuer and interest-rate risks.
- Fixed Deposits: Useful for liquidity and relatively predictable returns.
- Government Securities: Can form part of a stability-focused investment strategy.
The right allocation depends on individual circumstances rather than a universal investment formula.
3. Plan Around Military Retirement Benefits
Understand your applicable pension eligibility, retirement benefits, leave encashment and other service-related entitlements. Their treatment depends on the officer's service category and applicable government rules.
These benefits should be incorporated into an overall financial plan instead of being invested without a defined purpose.
4. Review Your Financial Plan Regularly
Promotions, postings, family responsibilities and changes in income can affect investment capacity. Review your portfolio and retirement goals at least annually.
A structured approach to retirement planning indian armed forces officers ensures that investments remain aligned with changing financial priorities.
Practical Example: An Army Officer With 10 Years Left in Service
Consider an illustrative Army officer who has approximately 10 years remaining before retirement.
The officer has accumulated mutual fund investments, fixed deposits and other savings but has never calculated the actual retirement corpus required.
A professional financial review could help identify:
- Current investments and their future projected value.
- Expected pension and retirement benefits.
- Outstanding loans and financial liabilities.
- Children's education requirements.
- Expected post-retirement household expenses.
- The additional investment required to meet retirement goals.
Based on this assessment, the officer can develop a goal-based investment strategy, balancing equity exposure, fixed-income investments and liquidity.
This demonstrates why retirement planning indian armed forces officers should focus on the complete financial picture rather than individual investment products.
Retirement Planning Checklist for Indian Army Officers
Before leaving military service, review the following:
- Calculate your estimated retirement corpus.
- Understand your applicable pension and retirement benefits.
- Maintain an adequate emergency fund.
- Review health and life insurance coverage.
- Plan separately for children's education.
- Evaluate outstanding loans and liabilities.
- Diversify investments across suitable asset classes.
- Account for inflation and taxation.
- Plan post-retirement monthly income.
- Review nominations and succession arrangements.
Conclusion: Build Financial Security Before Hanging Up Your Uniform
A successful military career deserves an equally well-planned financial future. Pension benefits provide an important foundation, but long-term financial independence requires disciplined investing, proper asset allocation and goal-based planning.
Starting early gives Army officers more flexibility to build wealth, manage financial risks and prepare their families for life beyond military service.
At Hum Fauji, the focus is on helping Indian Armed Forces personnel, veterans and their families make informed financial decisions through structured financial planning and wealth advisory.
If you are approaching retirement or still have several years of service remaining, consider getting your financial position reviewed. A well-designed retirement strategy today can help you enter your next chapter with greater financial confidence.