 Sign up with Google
 Sign in with Zoho
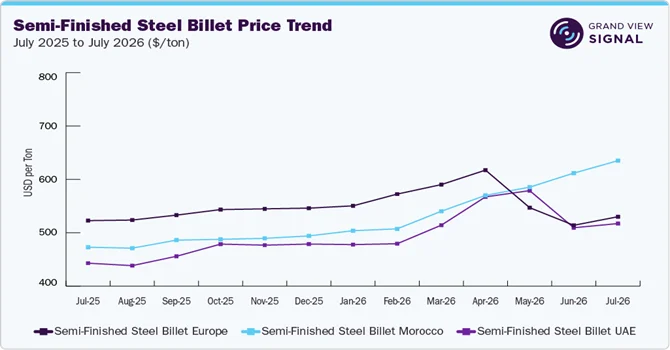
Covering iron ore, finished and semi-finished steel, and scrap grades, ferrous metals pricing intelligence provides critical clarity across volatile global supply chains. Navigating the global ferrous market requires balancing broad international trade shifts against local pricing pressures. This is especially true as raw material volatility tightens margins and strains purchasing budgets for steel mills. A clear example is the U.S. rebar market: while federal infrastructure funding drives an estimated 12.8% year-over-year expansion, fluctuating scrap costs for Electric Arc Furnaces (EAF) make tracking local supply and demand spreads essential.
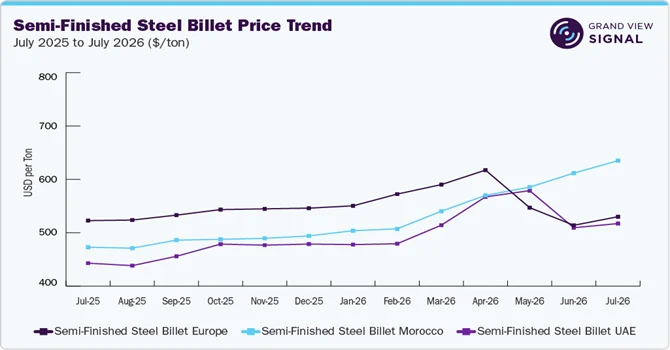
Platforms like Grand View Signal offer comprehensive pricing intelligence across the supply chain, giving commercial teams real-time price evaluations, regional arbitrage monitoring, and predictive forecasting.
Below are the five main drivers shaping iron ore, finished steel, and scrap markets today.
1. Chinese Iron Ore: Import Resilience Meets Expanding Supply
Despite ongoing weakness in China’s real estate sector, iron ore demand proved unexpectedly durable in mid-2026. Imports reached a six-month high as domestic steel mills restocked raw inputs to compensate for restricted local mining output. Steady daily crude steel production helped establish a solid price floor.
At the same time, supply routes are shifting. On January 17, a cargo carrying roughly 14,286 TEUs of iron ore arrived at Majishan Port in Zhejiang Province. Instead of coming from traditional suppliers like Australia and Brazil—which account for 69% and 21% of Chinese iron ore imports, respectively—this shipment came from Guinea. It marked the first maiden delivery from Simandou, the world’s largest undeveloped high-grade iron ore deposit.
New seaborne supply from Simandou, alongside consistent shipments from Australia and Brazil, has alleviated immediate shortage concerns. High port inventories have kept mills disciplined in their purchasing, prompting them to select higher-grade ores like Simandou's to improve blast furnace efficiency and lower emissions rather than stock up excessively.
- Key Indicators to Track: Monitor port inventory drawdowns against blast furnace utilization rates in major steel hubs like Tangshan, as well as monthly export volumes from Guinea’s new port facilities.
2. Domestic Chinese Steel: Consistent Output vs. Weather-Delayed Consumption
China’s domestic steel market displays a clear internal split. Crude steel production remains surprisingly steady, but downstream demand is lagging behind. Inventories across the five primary finished steel products rose 3.6% in early July as bad weather and weak construction activity stalled consumption.
Flat steel products like Hot-Rolled Coil (HRC) found mild support from manufacturing and export markets—despite a roughly 2.0% month-on-month drop in July 2026—whereas long steel products like rebar and wire rod experienced significant inventory accumulation. Muted property investment and squeezed margins have made mills reluctant to accept higher prices for inputs like iron ore, metallurgical coke, and scrap.
- Key Indicators to Track: Watch for a post-monsoon recovery in domestic rebar buying, and monitor whether mills begin voluntary production cuts to protect operating margins.
3. Asynchronous Regional Trends: Growth Spurt in India and the United States
Unlike China's property-driven slowdown, India and the U.S. provided important support for global steel consumption. India’s crude steel output grew 3.9% year-on-year in June, while finished steel production rose 6.0%. This strong internal demand helped protect Indian producers and sustain regional pricing.
In the U.S., disciplined supply management, scheduled mill maintenance outages, and ongoing trade protection helped stabilize the market. Even though buyers in both countries remain cautious about broader economic uncertainties, these markets serve as crucial counterweights to soft demand in Europe and China.
- Evaluating Regional Price Gaps: Wide price gaps between regions make cross-border arbitrage challenging to assess. Commodity intelligence platforms help commercial teams track regional price spreads—such as the gap between low Chinese HRC export offers and higher domestic quotes in the U.S. or India—enabling more effective export and procurement strategies.
- Key Indicators to Track: Follow the rollout of Indian infrastructure spending and track capacity utilization among major U.S. EAF operators as they complete maintenance turnarounds.
4. Rising Trade Protectionism Reroutes Global Steel Markets
Regulatory policies are increasingly driving global steel movements over basic market fundamentals. A growing number of trade defense measures—from preliminary anti-dumping duties on hot-dip galvanized steel in Japan to ongoing HRC investigations in India and tighter tariff-free import quotas in the UK—are altering traditional trade routes.
As major economies enforce national security tariffs and import quotas to protect domestic steelmakers from cheaper foreign imports, producers must redirect volume toward unshielded secondary markets. This regulatory friction creates price premiums in protected areas while depressing prices in open import destinations.
- Key Indicators to Track: Watch for final anti-dumping decisions in major Asian import markets and track potential shifts in trade flows toward Latin America and Southeast Asia.
5. Soft Seaborne Scrap Demand and European Summer Slowdowns
The deep-sea steel scrap market experienced a mid-year slump, largely due to reduced purchasing from Turkey, the world’s top scrap importer. Sluggish finished steel exports forced Turkish mills to maintain strict cost discipline, putting pressure on global Heavy Melting Scrap (HMS) benchmarks. As a result, prices dropped roughly 9.4% year-over-year to 320 USD/ton in July 2026.
In Europe, the annual summer holiday slowdown and low river levels on major waterways like the Rhine restricted barge transport and dampened scrap consumption. However, a structural divide is developing: lower-grade scrap remains under pressure, whereas prime industrial scrap commands a premium due to ongoing EAF expansions and green steel decarbonization targets.
- Monitoring Upstream Raw Materials: Advanced pricing tools allow market analysts to track spreads between deep-sea scrap, domestic scrap, and prime DRI/HBI alternatives, helping steelmakers optimize their furnace charge costs in real time.
- Key Indicators to Track: Look for a post-holiday recovery in Turkish deep-sea scrap orders, and monitor the price spread between prime industrial scrap and lower-grade HMS scrap as green steel initiatives grow.
Strategic Insight: Shifting from Reactive Purchasing to Predictive Market Intelligence
The iron ore and steel complex is moving away from unified global market cycles toward a fragmented, multi-speed landscape shaped by regional policies, weather disruptions, and trade protectionism.
Navigating this volatility requires commercial teams to move past static, historical data. By utilizing holistic market intelligence platforms like Grand View Signal, procurement teams and commercial strategists gain the real-time visibility needed to turn market shifts into a competitive advantage through:
- Monthly Price Assessments (Granular ASP Tracking): Access location-specific Average Selling Price (ASP) data across raw materials, polymers, and metals, preventing procurement teams from overpaying during sudden spot-market spikes.
- Longitudinal Historical Benchmarking: Review over ten years of structured pricing history across 200+ commodities, allowing commercial leaders to spot multi-year cycles and negotiate better contract terms.
- redictive Pricing & Forecast Modeling: Combine quantitative analytics with market variables to project short- and medium-term price trends, helping finance leaders transition to proactive, margin-protective sourcing strategies.
- Regional Risk & Volatility Analytics: Track trade barriers, tariffs, and logistics disruptions using volatility indices, allowing companies to optimize cross-border supply chains and take advantage of price arbitrage.
- Cost-Structure & Margin Decomposition: Break down commodity price points into raw input costs, shipping surcharges, and energy spreads, equipping commercial teams with the data needed to defend profit margins during contract negotiations.