Sign up with Google
 Sign in with Zoho
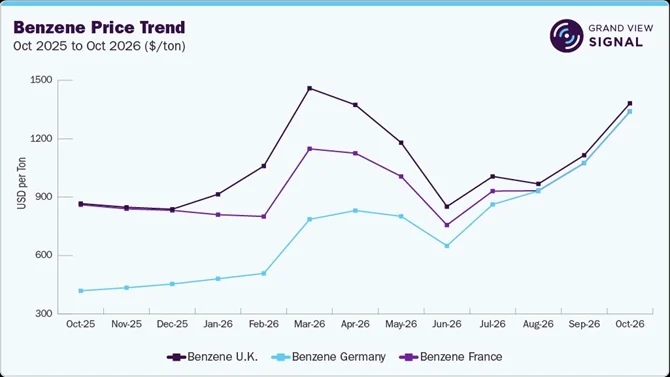
The global chemicals market continues to navigate a complex macroeconomic environment characterized by sharp structural shifts, fluctuating raw material costs, and divergent regional demand dynamics. Across organic and inorganic chemical sectors, market participants face persistent pricing volatility driven by upstream supply constraints on one end and selective purchasing resistance from downstream end-users on the other.
Navigating these market conditions requires an analytical approach supported by chemicals pricing intelligence that evaluates how primary feedstocks, operational adjustments, and trade balances interact across key manufacturing hubs. Drawing from real-time data provided by Grand View Signal, this analysis examines the key market drivers shaping current pricing structures across global distribution networks. Understanding these underlying mechanisms is essential for procurement managers, chemical manufacturers, traders, and strategic planners looking to manage input cost risks, protect profit margins, and maintain supply chain resilience. An evaluation of pricing intelligence reveals how feedstock pass-through dynamics, regional supply dependencies, and downstream buying behavior dictate pricing trajectories across the global landscape.
Organic Chemicals: Feedstock Pressures and Unbalanced Pass-Through Dynamics
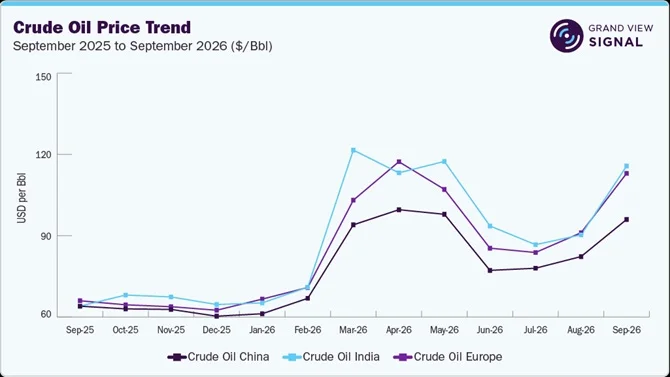
Upstream energy inputs exert an overwhelming influence on organic chemical pricing, with primary feedstock fluctuations demonstrating an 85%+ price correlation coefficient to intermediate and downstream derivative pricing across global spot markets. The organic chemical segment remains acutely sensitive to movements in primary upstream feedstocks, including crude oil, naphtha, benzene, propylene, and methanol. Fluctuations in these basic energy and petrochemical inputs create ripple effects throughout intermediate and downstream derivative chains. However, recent pricing patterns demonstrate that upstream cost inflation does not automatically translate into uniform price increases across all derivative products. Instead, the ability of producers to pass through feedstock costs depends heavily on local inventory levels, plant operating rates, and downstream demand sentiment.
Methanol and Derivative Chains
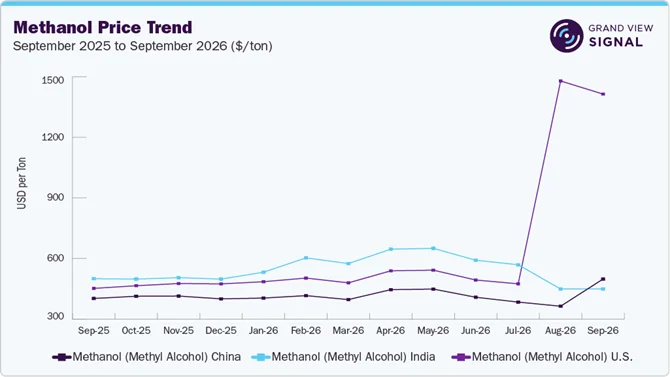
In the methanol sector, pricing trajectories reflect a delicate balance between tight upstream supply and cautious downstream consumption. Higher production and import costs have pushed baseline prices upward, particularly in coastal import hubs where inventory levels remain tightly managed. Upstream sellers have leveraged these tight coastal balances to defend higher asking prices. This market behavior is highlighted by methanol's performance, which recorded a 7.4% Month-over-Month (MoM) average price increase across key regional markets while maintaining a Medium Volatility Index, reflecting sustained cost pressure from tight coastal supply.
Despite these cost pressures, downstream derivative manufacturers, such as those producing formaldehyde, acetic acid, and olefin derivatives, face margin compression. In many regional markets, end-use buyers exhibit strong resistance to higher prices, purchasing strictly on a spot, hand-to-mouth basis rather than committing to long-term contract volumes. As a result, intermediate producers find themselves squeezed between rising methanol input costs and an inability to fully pass these increases to end customers without risking volume losses.
Acetate Solvents and Butyl Acetate Dynamics
A similar pattern of uneven pricing power is evident across the acetate solvent complex, particularly in the market for butyl acetate. Pricing for butyl acetate is heavily influenced by two primary raw materials: acetic acid and n-butanol. Recent market trends highlight a divergence in how these two feedstocks impact final product values.
On one side, acetic acid prices have received steady support from elevated upstream raw material costs and intentional reductions in plant operating rates by major producers. This firm upstream foundation has provided a baseline cost floor for acetate derivatives. On the other side, retreating prices for n-butanol have offset some of these acetic acid cost pressures, creating mixed pricing signals for butyl acetate manufacturers.
To prevent inventory accumulation and maintain price stability in the face of soft downstream demand from the coatings, inks, and adhesives sectors, solvent producers reduced average plant utilization rates to 65%–70% of total installed capacity. By curtailing output and executing planned maintenance turnarounds, manufacturers have successfully mitigated oversupply risks, keeping spot availability balanced relative to muted purchasing activity.
Operational Adjustments and Freight Impacts
Beyond raw material inputs, operational variables play a decisive role in shaping organic chemical price levels. Scheduled plant turnarounds, unexpected facility outages, and regional logistics bottlenecks frequently alter local supply-demand fundamentals. When major production units undergo maintenance, prompt product availability shrinks, temporarily shielding spot prices from broader macroeconomic weakness.
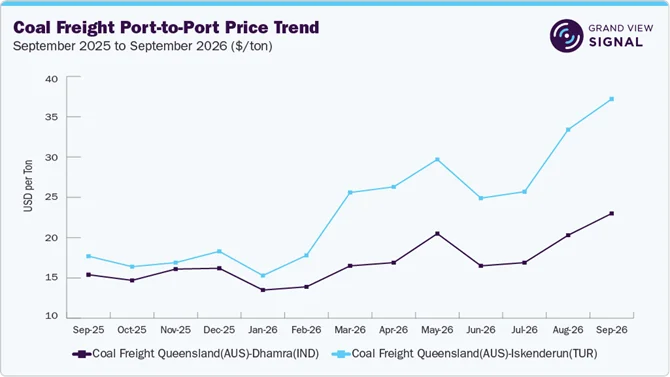
Furthermore, international freight disruptions and shifting trade routes have amplified price disparities between exporting and importing regions. Elevated shipping tariffs and extended transit times increase landed costs for imported organic chemicals, forcing domestic buyers to choose between high-cost imported spot cargoes or domestic supply secured under existing contract terms.
Inorganic Chemicals: Sourcing Constraints and Supply Security
While organic chemicals are primarily driven by energy and petrochemical feedstocks, inorganic chemical markets, including acids, alkalis, and mineral derivatives, are heavily influenced by raw material extraction costs, energy-intensive processing, and geopolitical trade flows. Current pricing intelligence highlights growing regional divergence in inorganic chemical values, largely dictated by local production economics and supply chain security.
The Sulphur and Mineral Acid Supply Chain
Sulphur represents one of the most critical foundational inputs in the inorganic chemical industry, serving as the primary feedstock for sulphuric acid production, which is subsequently consumed in vast quantities by the phosphate fertilizer, mining, and industrial chemical sectors. Consequently, volatility in global sulphur availability directly impacts the cost structure of mineral acid manufacturers worldwide.
Recent developments in global sulphur supply chains underscore the vulnerability of downstream acid markets to upstream disruptions. Sulphur, produced primarily as a byproduct of oil refining and natural gas processing, is subject to shifting international refining yields and environmental regulations. When refiners alter processing slates or reduce throughput, elemental sulphur output contracts, tightening global spot availability.
This tight upstream supply environment forces sulphuric acid and phosphoric acid manufacturers to navigate rising raw material costs. In regions reliant on imported elemental sulphur, acid producers face substantial cost escalation, which trickles down into industrial applications ranging from chemical synthesis to metal processing. The strategic priority for inorganic producers has consequently shifted toward securing long-term feedstock supply agreements to hedge against spot market volatility.
Regional Market Intelligence: China and India Focus
Global chemical pricing dynamics manifest differently across key Asian manufacturing hubs, reflecting distinct industrial structures, import dependencies, and domestic demand profiles.
China: Upstream Resilience Meets Downstream Caution
In China, a critical center for the broader chemicals market, recent price movements highlight a clear divide between upstream manufacturing discipline and downstream purchasing sentiment. Across several organic chemical chains, Chinese producers have successfully supported price levels by managing facility operating rates and maintaining disciplined inventory targets.
However, downstream sectors, including resins, industrial coatings, textiles, and domestic consumer goods, continue to exercise purchasing restraint. Buyers in these sectors are closely managing working capital, choosing to procure spot volumes only to fulfill immediate order books rather than accumulating buffer stock. This cautious buying behavior creates a price ceiling for many commodity chemicals, preventing sustained upward rallies despite elevated raw material costs. Prompt product availability remains sufficient to meet ongoing demand, preventing panic among buyers and keeping market negotiations tightly focused on incremental price adjustments.
India: Import Exposure and Feedstock Vulnerabilities
In contrast to China's expansive domestic manufacturing base, India's chemical landscape is characterized by high exposure to imported raw materials, particularly across the inorganic acid and fertilizer sectors. Indian manufacturers of sulphuric acid, phosphoric acid, and specialized inorganic compounds rely heavily on overseas supply chains for elemental sulphur and key mineral inputs.
With domestic acid manufacturers reliant on overseas supply for over 60% of their elemental sulphur inputs, recent international shipping bottlenecks and fluctuating global sulphur prices have directly increased landed production costs, straining operating margins when domestic end-users resist price increases. Supply chain security has therefore emerged as the principal operational challenge for Indian chemical procurement teams, prompting a stronger focus on diversifying import sources and establishing long-term strategic supply relationships.
Strategic Takeaways for Procurement and Industry Leadership
The ongoing interaction between feedstock volatility, operational adjustments, and downstream buying resistance requires chemical industry leaders to adopt proactive market tracking and procurement strategies. Relying solely on historical price trends or trailing monthly averages is no longer sufficient in a market driven by rapid supply-side shifts.
To maintain a competitive edge, procurement organizations must implement high-frequency price intelligence systems that monitor both upstream feedstock benchmarks and downstream demand indicators. Platforms like Grand View Signal empower decision-makers with transparent data metrics, such as crude oil shifts, plant turnaround schedules, regional freight rates, and import availability, allowing purchasing teams to anticipate price turns before they materialize in formal vendor quotes.
Additionally, decision-makers should continually re-evaluate supplier contract structures against dynamic average selling price (ASP) benchmarks. By aligning procurement schedules with regional supply cycles and establishing flexible indexing mechanisms tied to core feedstocks, companies can protect their operating margins against sudden price spikes while optimizing raw material costs during market downturns.