 Sign up with Google
 Sign in with Zoho
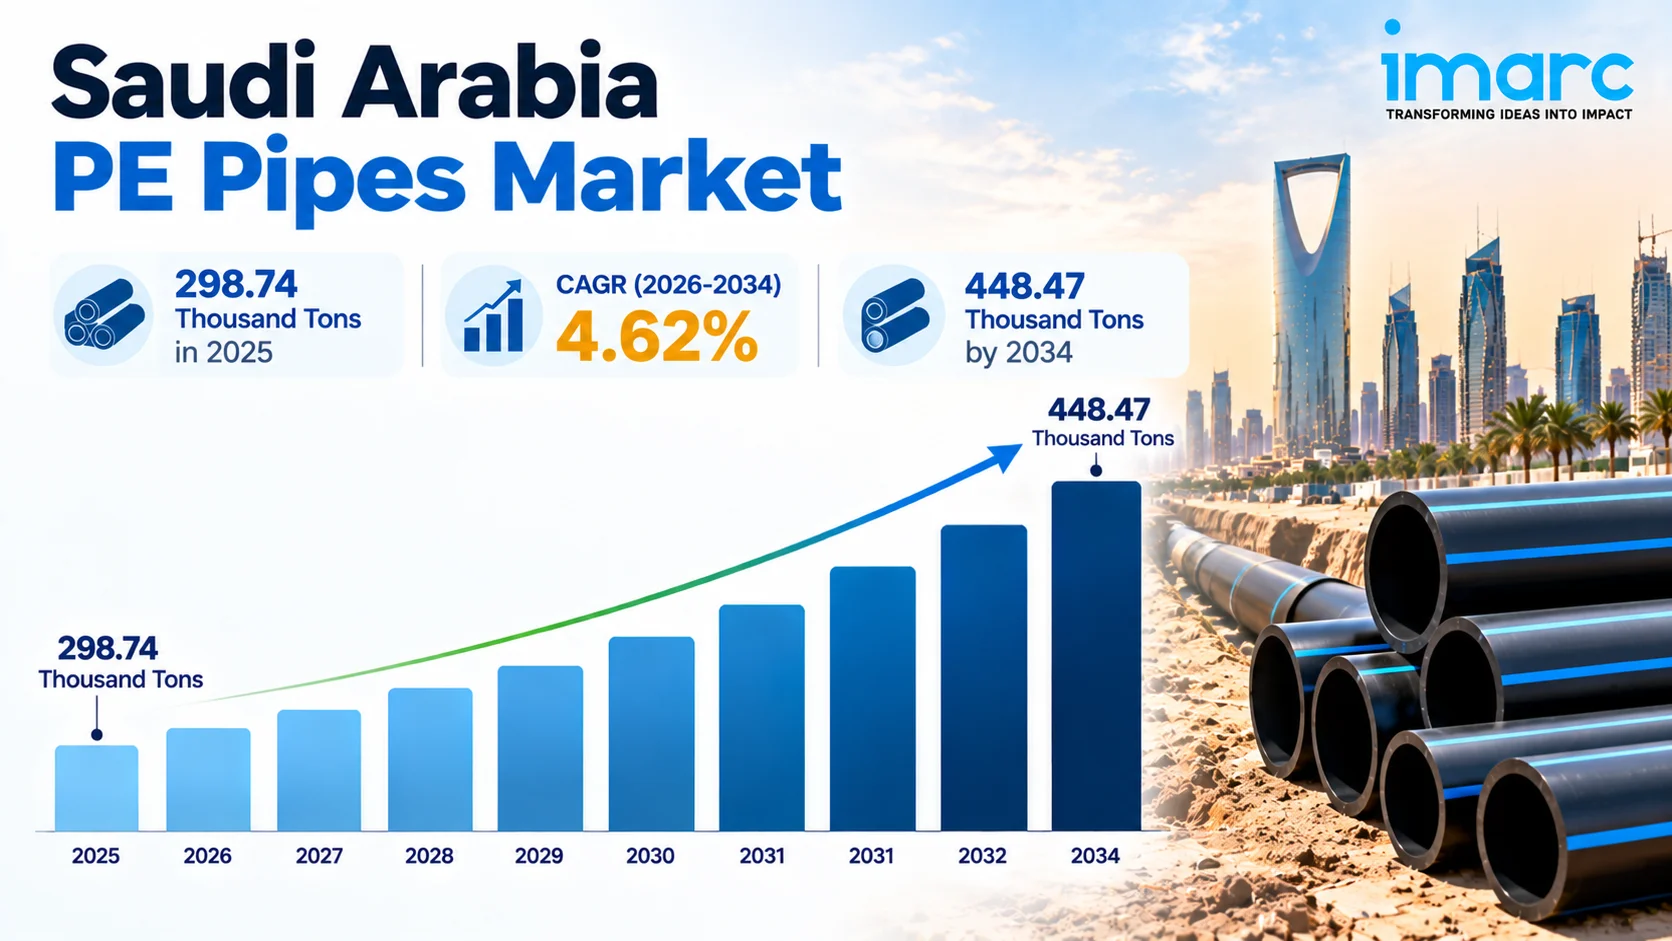
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia PE pipes market. The Saudi Arabia PE pipes market reached 298.74 Thousand Tons in 2025 and is projected to reach 448.47 Thousand Tons by 2034, exhibiting a CAGR of 4.62% during 2026-2034, driven by Vision 2030 infrastructure programs, accelerating investment in water distribution networks, and expanding oil and gas activity.
PE pipes benefit from the non-discretionary nature of water, sanitation, and energy infrastructure spending in Saudi Arabia, with every new smart city, residential community, industrial zone, and pipeline expansion requiring durable, corrosion-resistant piping systems for harsh desert conditions. The market is forecast to add approximately 149.73 Thousand Tons in volume between 2025 and 2034, with three structural forces shaping this trajectory: government-led modernization of aging water infrastructure, large-scale oil and gas pipeline network development, and rapid urbanization with a booming real estate pipeline.
Saudi Arabia PE Pipes Market at a Glance:
- Market Size (2025): 298.74 Thousand Tons
- Forecast Market Size (2034): 448.47 Thousand Tons
- CAGR (2026-2034): 4.62%
- Leading Type (2025): HDPE, 62.9% share
- Leading Application (2025): Water Supply, 54.2% share
- Base Year / Forecast Period: 2025 / 2026-2034
How AI is Reshaping the Future of the Saudi Arabia PE Pipes Market
- IoT-Enabled Smart Pipeline Networks: Digital monitoring systems and IoT-integrated pipeline networks are becoming standard practice in new smart city developments, giving municipal authorities real-time visibility into flow, pressure, and network health across PE installations.
- AI-Ready Leak Detection and Water Conservation: The National Water Company piloted a fibre-optic-based leak detection project in Burayada in 2024, signaling the shift toward intelligent infrastructure where data-driven analytics help minimize water losses in an arid, desalination-dependent Kingdom.
- Advanced Manufacturing and Material Innovation: Pipe manufacturers are investing in advanced production technologies, insulated PE systems, and thermoplastic composite and reinforced polymer solutions to deliver higher durability, thermal efficiency, and consistent quality for demanding water, district cooling, and oil and gas applications.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-pe-pipes-market/requestsample
Saudi Arabia PE Pipes Market Trends and Drivers:
Government investment in water infrastructure modernization is the foundational driver behind Water Supply's dominant 54.2% application share in 2025, as ongoing initiatives to expand distribution networks and replace aging pipelines address the challenges of water management in an arid environment that relies heavily on desalination. In April 2025, NWC commenced 16 water and wastewater projects in the Qassim region valued at SAR 1.1 billion (USD 293 million), including water pipelines extending over 579 kilometers. HDPE leads the type mix at 62.9% share, reflecting its superior mechanical strength, flexibility, corrosion resistance, and suitability for water supply, sewage, and gas distribution across the Kingdom.
Oil and gas sector expansion is compounding this water-led growth with sustained demand for corrosion-resistant piping across upstream and midstream operations. Aramco's Master Gas System Phase 3 expansion involves 4,153 kilometers of pipeline network at an estimated cost of USD 18 billion, while the Jafurah unconventional gas development program is expected to exceed USD 110 billion in lifecycle investment. Meanwhile, rising adoption of insulated piping is gathering pace, with Perma-Pipe International Holdings securing USD 10 million in contracts in July 2024 for infrastructure projects in Riyadh, Madinah, and Mekkah, and Strohm securing a contract in January 2025 to supply 33 kilometers of thermoplastic composite pipes for Aramco's Fadhili gas plant expansion.
Rapid urbanization and real estate development are reshaping demand on top of these drivers. The Saudi Arabia real estate market was valued at USD 77.2 Billion in 2025 and is expected to reach USD 137.8 Billion by 2034 at a CAGR of 6.70% during 2026-2034, creating substantial pipeline requirements across smart cities, entertainment districts, and integrated housing communities. Regulatory reforms, localization initiatives, and private-sector participation under Vision 2030 are simultaneously strengthening domestic manufacturing capabilities and technology transfer, while challenges such as raw material price volatility, competition from steel, ductile iron, and concrete, and strict technical certification requirements continue to shape competitive dynamics.
Government Schemes and Vision 2030 Initiatives Driving Demand:
- Vision 2030 Infrastructure Development: A core national transformation agenda promoting large-scale infrastructure, urban expansion, and water and wastewater management projects, with mega-projects including smart cities, industrial zones, and residential communities driving demand for durable and cost-efficient piping solutions.
- National Water Company (NWC) Investment Programs: Long-term public investment in water and sanitation infrastructure is creating sustained demand for polyethylene piping, including the SAR 400 million desalinated water project completed in April 2025 across three governorates in the Riyadh region.
- Riyadh Sewage System Expansion: In October 2024, NWC announced plans to award a USD 40 million contract for the Riyadh sewage system expansion, specifying 18.5 kilometers of HDPE pipes with diameters ranging from 200mm to 500mm.
- Sustainability and Water Efficiency Goals: Vision 2030 sustainability and efficiency targets are encouraging adoption of advanced PE materials that reduce leakage and energy losses, supporting the transition toward sustainable construction practices.
- Localization and Private-Sector Participation: Regulatory reforms and localization initiatives are strengthening domestic manufacturing capabilities, fostering technology transfer, and reducing import dependence as companies invest in advanced production facilities.
Saudi Arabia PE Pipes Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Type:
- HDPE
- MDPE
- LDPE
- LLDPE
HDPE commands a 62.9% majority share in 2025, driven by its superior mechanical strength, durability, and resistance to high temperatures, pressure fluctuations, and corrosive soil conditions commonly found across the Kingdom. Its flexibility and lightweight nature enable faster installation, lower overall project costs, and compatibility with trenchless installation methods, making it the preferred choice for water supply, wastewater, and industrial piping applications.
Breakup By Application:
- Water Supply
- Irrigation
- Sewerage and Drainage
- Gas Supply
- Mining and Slurry Lines
- Others
Water Supply dominates at 54.2% share in 2025, the largest and most consistent demand category, sustained by the Kingdom's arid climate, heavy reliance on efficient water distribution networks, ongoing urban expansion, and population growth. PE pipes are widely preferred for water supply because of their corrosion resistance, flexibility, long service life, low maintenance requirements, and joint integrity across diverse terrains. In April 2025, NWC's 16 projects in the Qassim region alone included water pipelines extending over 579 kilometers.
Competitive Landscape:
The Saudi Arabia PE pipes market exhibits moderate competitive intensity, with established domestic manufacturers competing alongside regional players. The report provides detailed profiles of all major companies, including:
- Saudi Plastic Products Company Ltd. (SAPPCO)
- Alwasail Industrial Company
- Arabian Gulf Manufacturers Ltd.
- Saudi Arabian Amiantit Company
- Al Jubail Sanitary Pipe Factory
- IKK Group
Leading companies are expanding production capacities, enhancing product quality, and adopting international standards to meet growing infrastructure demand. Collaborations with construction and utility sectors are being strengthened to secure large-scale project contracts, with emphasis on sustainability and cost efficiency, while manufacturers are also exploring export opportunities within the Gulf region.
Market Concentration Analysis:
- Competitive Intensity: The market exhibits moderate competitive intensity, with established domestic manufacturers competing alongside regional players across product segments
- Capacity and Technology Investment: Key participants are expanding production capacities and investing in advanced manufacturing technologies to meet growing infrastructure demand
- Entry Barriers: Strict technical standards and certification requirements favor well-established enterprises with certified processes and developed quality management systems, while innovation and customization options are gaining traction across water supply, sewage, and oil and gas applications
What Does The Full Report Cover?
If you are tracking the Saudi Arabia PE pipes market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
- Complete market sizing in volume terms (Thousand Tons) with forecasts covering the full 2026-2034 projection period and historical data for 2020-2025
- Growth driver and restraint analysis covering government water infrastructure investment, oil and gas expansion, urbanization, raw material volatility, and certification requirements
- Sub-segment breakdowns for four types and six applications, each with individual share and growth insights
- Competitive profiles of SAPPCO, Alwasail Industrial Company, Arabian Gulf Manufacturers, Saudi Arabian Amiantit Company, Al Jubail Sanitary Pipe Factory, and IKK Group with strategic positioning analysis
- Latest trends covering smart city development, insulated piping solutions, advanced non-metallic piping technologies, and Vision 2030-driven localization opportunities shaping market competition across the Kingdom
Recent News and Developments in Saudi Arabia PE Pipes Market
- April 2025: NWC completed a SAR 400 million project delivering desalinated water to three governorates in the Riyadh region, demonstrating the scale of ongoing infrastructure investments driving demand for PE piping systems.
- January 2025: SABIC unveiled its new polypropylene pipe solution, SABIC VESTOLEN P9421, manufactured with a random copolymer, offering high thermal stability, durability, and resistance to high pressures and temperatures for cold and hot water pipe applications.
- October 2024: Saudi Vitrified Clay Pipe Co. (SVCP) and Qatar's Laffan Pipes Factory signed an agreement to establish a joint venture focused on producing and trading durable pipes and related components, enhancing production capabilities to meet growing regional infrastructure demand.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia PE pipes market size and what is its projected volume?
- Which type and application hold the largest share in the Saudi Arabia PE pipes market?
- What are the key drivers of Saudi Arabia PE pipes market growth?
- What challenges, including raw material volatility and competition from alternative materials, is the market facing?
- How is Vision 2030 reshaping the Saudi Arabia PE pipes industry through infrastructure, water, and localization initiatives?
- Who are the top companies in the Saudi Arabia PE pipes market and what are their competitive strategies?
- What are the investment and market entry opportunities across water supply, gas distribution, and advanced piping technologies in Saudi Arabia?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104