 Sign up with Google
 Sign in with Zoho
There's a version of no cost credit card processing that exists mainly in marketing copy. The headline says zero fees, the fine print reveals a monthly subscription, an equipment lease, a minimum processing requirement, or a rate structure that quietly recovers everything the headline promised to eliminate. Business owners who have been burned by this pattern once tend to approach any claim of free or zero-cost processing with the kind of skepticism that's completely earned. What Dual Payments offers is different, and the difference is structural rather than cosmetic. The model genuinely eliminates processing costs for the merchant rather than moving them around or hiding them somewhere less visible.
How No Fee Credit Card Processing Works in Practice
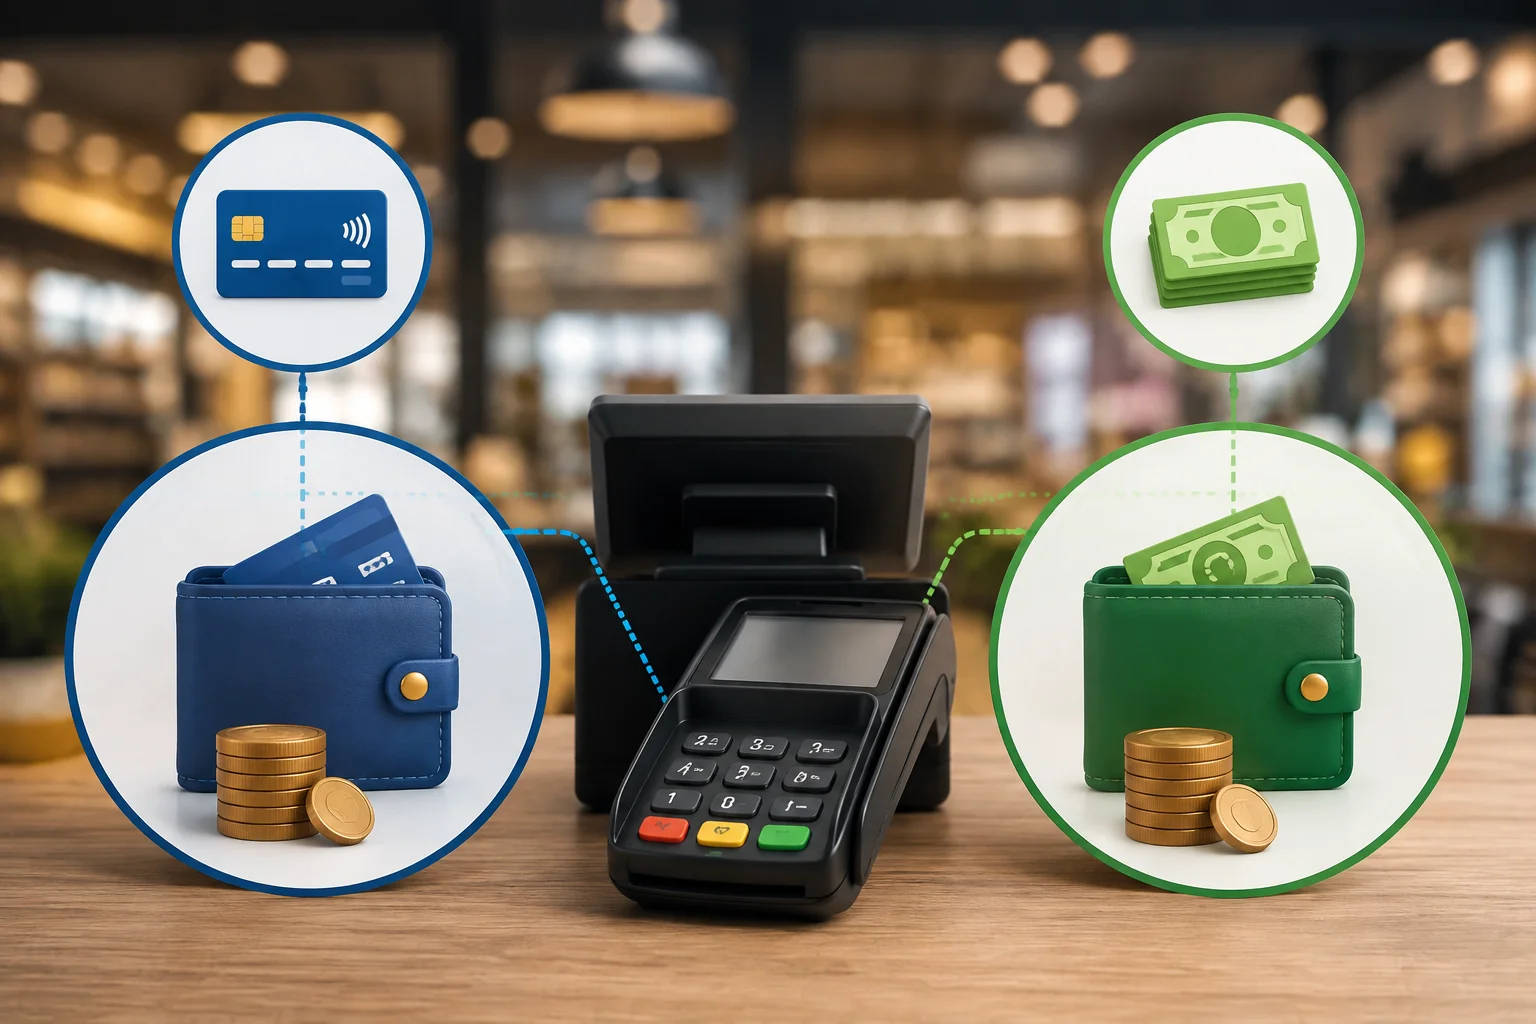
No fee credit card processing through Dual Payments is built on the dual pricing and cash discount model, which is worth understanding properly before dismissing it as too good to be true. The mechanics are genuinely straightforward. Two prices are displayed at the point of sale: a cash price and a card price. The card price reflects the standard item price plus the processing fee that would otherwise be absorbed by the merchant. Cash-paying customers pay the lower price. Card-paying customers pay the higher price that covers the processing fee. The merchant receives the same net amount regardless of which payment method the customer chooses.
This is not a surcharge program in the traditional sense, and it's not the same as simply raising all prices and hoping customers don't notice. It's a transparent dual pricing model that is legal across all 50 states when implemented with the correct signage and compliant POS setup. Dual Payments provides both, meaning merchants don't have to figure out compliance independently or worry about implementing something incorrectly.
Zero-Cost Credit Card Processing for Every Business Type
Zero-cost credit card processing is accessible to a much wider range of business types than most people initially assume. Retail, food service, professional services, healthcare, high-risk merchants, the dual pricing model works across virtually every sector where card payments are accepted. The customer-facing experience is clean and transparent, and most customers are far more accepting of the cash versus card price distinction than merchants initially expect.
The businesses that tend to be most surprised by the customer response are the ones that assumed pushback would be significant. In practice, customers encounter dual pricing regularly enough at fuel stations and other retailers that the concept is familiar. Clear signage and a POS display that shows both prices at checkout handles the communication without requiring any awkward conversation at the register. Customers see the difference, choose their payment method accordingly, and the transaction completes without friction.
No Cost Credit Card Processing That Includes Free Equipment
Equipment is where a lot of zero-cost processing claims fall apart. The processing might technically be free but the terminal costs several hundred dollars, the POS software carries a monthly fee, or the setup requires purchasing hardware that the processor then finances at an unfavorable rate. No cost credit card processing through Dual Payments includes the equipment at no charge because the model doesn't need to recover those costs through equipment financing.
Merchants who switch to the Dual Payments cash discount program receive a POS system and credit card terminal free of charge. The equipment is EMV-capable, accepts all major cards and mobile payments, and integrates with the dual pricing software so that cash and card prices display correctly at checkout without manual adjustment. Setup is designed to be completed quickly without technical expertise, and support is available through the process for merchants who have questions.

.webp)