 Sign up with Google
 Sign in with Zoho
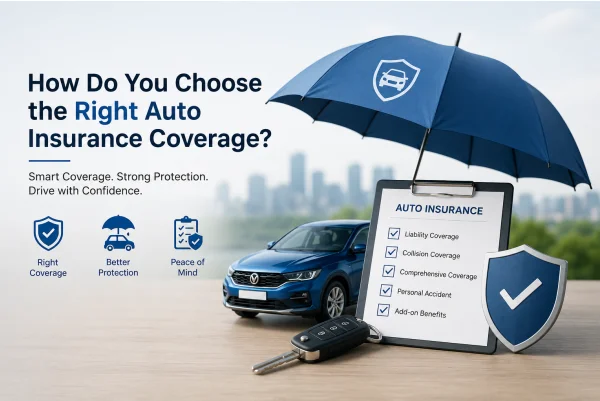
A good insurance policy does much more than satisfy legal requirements—it protects your savings, reduces financial stress after an accident, and gives you confidence every time you drive. However, with so many policy options, coverage limits, and add-ons available, selecting the right plan can feel overwhelming.
Many drivers also wonder whether factors like does an uninspected car raise insurance rates or affect policy approval. Understanding how insurers evaluate your vehicle helps you avoid surprises and choose coverage that truly matches your needs instead of paying for unnecessary protection.
Understanding Why Coverage Matters Before You Buy
Auto insurance is not simply about paying a yearly premium. It is about protecting yourself from unexpected financial losses that could arise from accidents, theft, natural disasters, or third-party liabilities. Every driver has different needs based on the age of the vehicle, driving habits, location, and financial situation. Spending a little time understanding your options today can prevent significant expenses tomorrow.
Understand the Different Types of Auto Insurance
Before selecting a policy, it's important to understand what each type of coverage actually provides. Liability insurance generally pays for injuries and property damage caused to others if you are responsible for an accident. Collision coverage helps repair your own vehicle after an accident, while comprehensive insurance protects against theft, fire, floods, vandalism, falling objects, and many other non-collision incidents.
Many insurers also offer optional benefits like roadside assistance, engine protection, zero depreciation cover, return-to-invoice benefits, and personal accident coverage. Choosing only the options that genuinely fit your driving lifestyle helps keep your premium affordable.
Evaluate the Value of Your Vehicle
The type of vehicle you own plays a significant role in determining the insurance you should purchase. A brand-new car often deserves broader protection because repair or replacement costs can be substantial. Older vehicles with lower market value may not require every optional add-on.
If you have financed your vehicle, lenders usually require comprehensive protection throughout the loan period. This is why many buyers search for do you need full coverage on a financed car before choosing an insurance policy. Understanding your financing agreement ensures you stay compliant while protecting your investment.
Compare Coverage Instead of Only Comparing Prices
Many drivers focus entirely on finding the cheapest premium, but lower prices often come with reduced protection. A policy that appears inexpensive today may leave you paying thousands from your own pocket after an accident.
Instead of comparing premiums alone, evaluate claim settlement records, customer service, repair network availability, deductibles, exclusions, and coverage limits. A balanced policy that offers dependable protection is usually a smarter long-term investment than the lowest-priced option.
Choose Coverage That Matches Your Driving Habits
Every driver uses their vehicle differently. Someone who drives daily through heavy city traffic faces different risks than someone who drives only on weekends. Long-distance commuters may benefit from higher coverage limits because they spend more time on the road, increasing their exposure to potential accidents.
Similarly, if you regularly travel through areas prone to flooding or severe weather, comprehensive coverage becomes more valuable. Matching insurance to your driving pattern helps ensure you receive protection where it matters most.
Don't Ignore Deductibles
A deductible is the amount you agree to pay before your insurer covers the remaining repair costs. Choosing a higher deductible generally reduces your annual premium, but it also increases your out-of-pocket expense during a claim.
The right deductible depends on your financial situation. If you have emergency savings, a slightly higher deductible may help reduce yearly insurance costs. If unexpected repair bills would be difficult to manage, selecting a lower deductible may provide greater financial security.
Review Add-On Covers Carefully
Insurance companies often promote numerous optional add-ons. While some provide excellent value, others may not be necessary depending on your vehicle and driving habits.
Zero depreciation cover can significantly reduce repair expenses for newer cars, while roadside assistance may be worthwhile for people who frequently travel long distances. Engine protection can also be valuable in regions that experience heavy rainfall and waterlogging. Selecting only relevant add-ons ensures you receive meaningful benefits without unnecessarily increasing your premium.
Understand What Full Coverage Really Means
Many people assume "full coverage" means absolutely every situation is covered, but that isn't always true. Every insurance policy contains exclusions, limits, and conditions that determine when claims are approved.
Before purchasing any policy, take time to understand what does full coverage car insurance cover. Reading the policy documents carefully helps prevent misunderstandings and allows you to know exactly what protection you are paying for.
Read the Fine Print Before Purchasing
Insurance contracts contain important details regarding exclusions, waiting periods, claim procedures, depreciation rules, and documentation requirements. These sections are often overlooked but become extremely important during claim settlement.
Understanding the policy before signing helps eliminate confusion later. A few extra minutes spent reviewing the terms can save both money and frustration if you ever need to file a claim.
Reassess Your Coverage Every Year
Your insurance needs can change over time. The value of your vehicle decreases, your driving habits may evolve, and insurance companies regularly introduce improved plans with better pricing.
Reviewing your policy before renewal gives you an opportunity to adjust coverage, remove unnecessary add-ons, increase protection where needed, and potentially lower your premium. Regular policy reviews help ensure your insurance continues to match your current circumstances.
Conclusion
Choosing the right auto insurance coverage is about finding the balance between affordability and meaningful protection. Instead of focusing only on the cheapest premium, consider your vehicle's value, driving habits, financial situation, and the risks you are most likely to face. Understanding how different coverages work, comparing insurers carefully, and reviewing your policy each year can help you make a confident decision. Taking the time to choose wisely today ensures that when unexpected events occur, your insurance works exactly as you expect and provides the financial protection every responsible driver needs. Remember to understand what does full coverage car insurance cover before finalizing your policy so you know precisely what level of protection you're receiving.