 Sign up with Google
 Sign in with Zoho
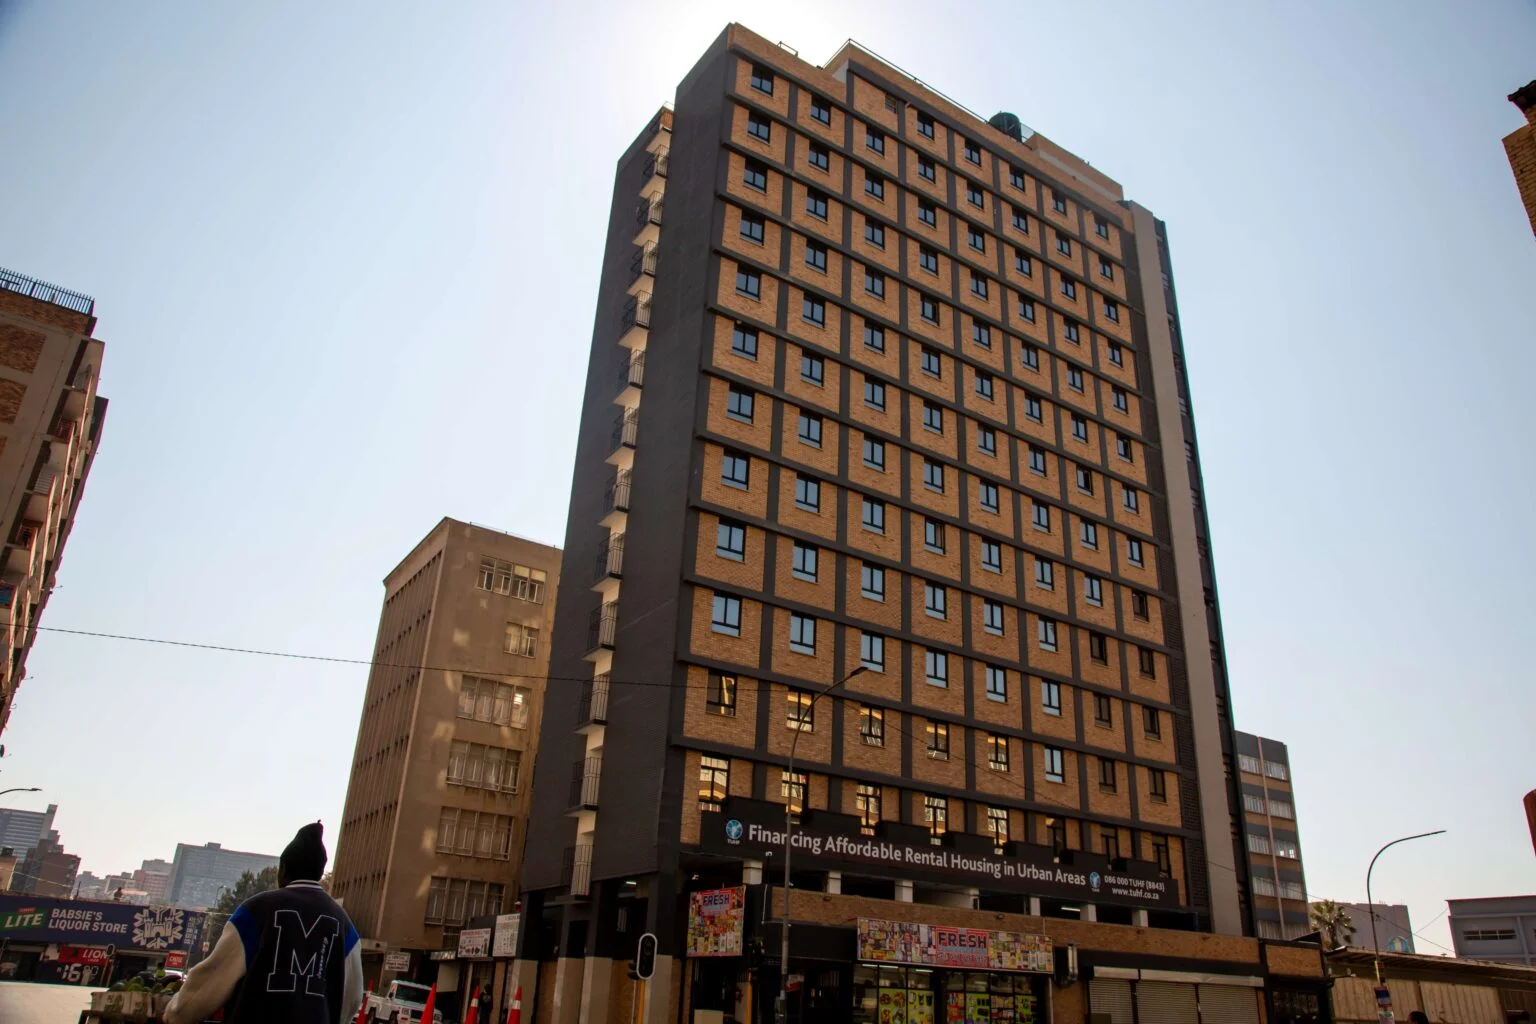
Are you building a property from scratch? Alternatively, you may have undertaken a major refurbishment project. Irrespective of the purpose, you will require development finance. This specialised loan is for developers who want to buy land or sites for construction of buildings for residential, commercial or mixed-use purposes.
How it works
A traditional mortgage can last for several years. In contrast, development finance is generally repaid within nine months to three years. Thus, it is a short-term solution. Secure loans with fast approvals from Property Development Finance Lenders South Africa. The following post explains the complexity of this concept and offers a clear understanding of how this specialised loan works.
About the process
These funds support property projects right from acquisition to the completion phase. The funds are not released all at once, but rather they are allocated in stages with the progress of the project. The funds for the project are tailored as per the requirements. Real estate projects get support for acquisition and construction from Financing Property Developments resources.
Gain an insight
The funding package is not simple. Most lenders give serious consideration to applications above £150,000. For smaller projects, other types of development finance such as buy-to-sell bridging loans or personal loans are available. Each scheme may vary, but the process adheres to a consistent path.
Identification of the site
The developer is responsible for identifying a viable site. Is the developer the owner of the underlying land? If the planning permission is ready, securing a loan is a straightforward procedure. Not all developers are owners of the land. In most cases, the land needs to be purchased. Under such circumstances, a developer can apply for a short-term bridging loan before refinancing into a development facility.
Funding proposal
As soon as the developer reaches the conclusion that a development finance loan is suitable, the next step involves submission of a funding proposal. They include major details such as:
Gross development value
You will have to estimate the projected market value of the development after the units are complete. This figure is necessary to ascertain the amount you can borrow.
Estimated costs
You will need a breakdown of all elements of construction expenses. This category includes materials, professional fees, and provision for contingencies. This is necessary for lenders to determine project viability.
Planning status
Do you have full planning permission? Or is it still pending? In general, lenders are in favour of fully consented schemes, but in certain cases they may fund pre-planning schemes.
Exit strategy
How do you intend to make the loan repayment? You can sell the completed units or opt for refinancing. A clearly defined strategy is essential for securing finance. At this juncture, indicative terms may be offered.
Assessment of the lender
If the indicative terms sound favourable, the developer will furnish more detailed information. The lender’s underwriter will consider the project’s viability, the experience of the developer, and the exit plan. The amount a developer can borrow relies on certain parameters such as the gross development value, equity contribution and the projected cost.
Assessment by a certified professional
The lender will contact a certified quantity surveyor to assess the current value of the land or building. Lenders use this to determine their lending limits. However, the lending parameters will vary from one lender to another.
Due diligence
The lenders will seek solicitors to carry out checks on the title of land, planning permission and prevailing restrictions. After these checks, final documentation is made ready. The loan agreement comprises the transaction terms.
All about drawdowns
The formalities are completed after the signing of the documents. Funds are withdrawn in stages. The loan drawdown feature ensures that the loan is being used on site appropriately.
Repayment of loan
At the end of the project, developers repay the debt to the lending institution using either of the following methods. The proceeds from selling the new units are used to pay off the principal and interest on the loan. The remaining portion that is left over is considered the developer's profit. The developer may retain the property as an income-generating asset. In that case, the short-term construction loan is replaced with a lower-interest, long-term commercial mortgage or investment loan with the support of the rental income.
Concluding note
If you want to attain success in your real estate project, you must have a solid understanding of business financing. Get a clear picture of the diverse financing options available in the market. But with the right plans and good structure you can turn your property development dreams into reality. Minimize your risk by working with experienced professionals. Do your homework properly. Do not skip the research phase. Otherwise, a wrong decision may lead to disastrous results. Find a bank which is a well-established name in the industry.