 Sign up with Google
 Sign in with Zoho

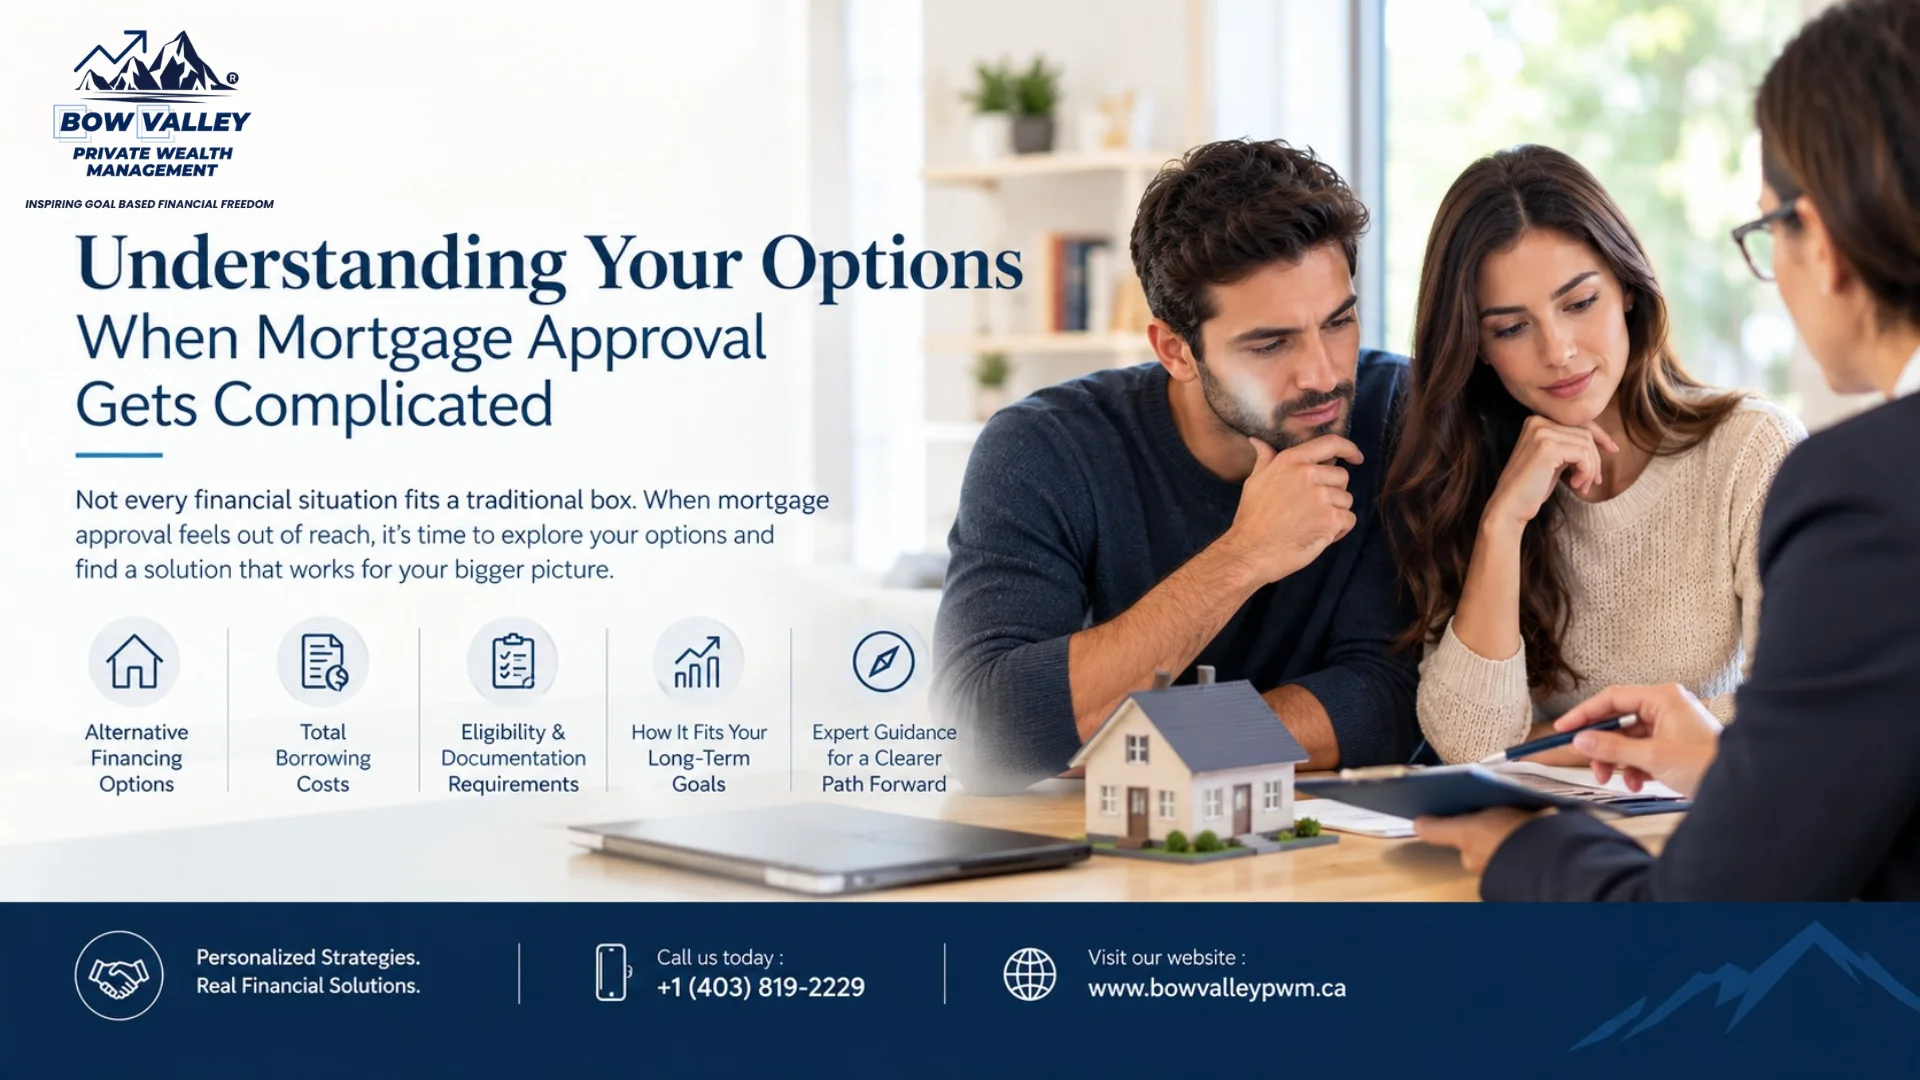
Getting a mortgage isn’t always as straightforward as finding a home, filling out an application, and waiting for a yes. Sometimes your income is unusual, your credit history has a few bumps, or you’re dealing with a property that doesn’t fit a lender’s standard box.
That’s where a Private Mortgage Lender may become part of the conversation.
But here’s the thing: alternative financing shouldn’t be viewed as a shortcut or a magic solution. It’s a financial decision, and the numbers need to make sense beyond the day you receive the funds.
When a Private Mortgage Lender May Enter the Picture
Traditional lenders have qualification rules, and borrowers are assessed based on factors such as income, debt, credit history, property details, and affordability.
Not every borrower fits neatly into those requirements.
You might be self-employed with income that’s difficult to document in a traditional way. Maybe you’re purchasing an unusual property. Perhaps you’re working through a temporary credit problem or need financing on a tighter timeline.
In situations like these, a Private mortgage lender may offer an alternative route.
That doesn’t mean it’s automatically the right route.
It simply means there’s another financing structure worth understanding.
Look Beyond the Interest Rate
I’ve seen people focus heavily on one number: the interest rate.
Of course, the rate matters. But it’s not the entire mortgage.
You also need to look at the term, payment structure, lender fees, legal costs, renewal conditions, discharge fees, and potential penalties.
A mortgage can look affordable at first glance and become considerably more expensive once all the costs are added together.
The Financial Consumer Agency of Canada recommends understanding mortgage terms, interest, penalties, and other charges before signing.
That’s not exactly exciting reading—but neither is discovering an unexpected fee after you’ve signed.
What’s the Exit Plan?
This is one question I’d put near the top of the list:
“What happens next?”
If you’re using alternative financing because you don’t currently qualify for traditional financing, the goal shouldn’t simply be to get the mortgage today.
You should understand what could allow you to move into a different financing arrangement later.
For example, perhaps your income will become easier to document, your credit profile may improve, or you expect to reduce other debts.
That future possibility needs to be realistic—not just something that sounds good on paper.
A Mortgage Should Fit Your Bigger Financial Picture
Your mortgage doesn’t live on an island.
It affects your monthly cash flow, savings capacity, investment decisions, retirement goals, and ability to handle unexpected expenses.
Suppose you’re approaching retirement and already have significant monthly obligations. Taking on a more expensive mortgage could affect how much you’re able to put toward retirement savings.
That’s where Retirement Planning Calgary becomes relevant.
The question isn’t only, “Can I qualify?”
It’s also, “How does this decision affect the financial life I’m trying to build?”
Those are two very different questions.
Don’t Ignore Other Financial Commitments
The same thinking applies if you have existing debt or are working through financial restructuring.
For someone exploring CIRP Financial Planning, mortgage decisions may need to be considered alongside debt obligations, cash flow, assets, and longer-term financial goals.
Adding another loan without understanding the complete picture can create more pressure rather than solving the original problem.
Sometimes the smartest financial decision is not the one that gets you the largest amount of money.
It’s the one that keeps the overall plan workable.
What About Investments?
There’s another common mistake: treating investment income as a guaranteed solution for mortgage costs.
You might see High yield exchange traded funds promoted as an attractive way to generate income.
But “high yield” doesn’t mean “risk-free,” and investment returns aren’t guaranteed simply because a fund distributes income.
If you’re considering investments while carrying mortgage debt, look at both sides of the equation.
How much are you paying to borrow?
What level of investment risk are you taking?
Can you comfortably handle a period of weaker investment performance?
And most importantly, does the strategy fit your actual financial goals?
A Real-World Example
Imagine a self-employed Calgary business owner who wants to purchase a property.
Their business is profitable, but their income documentation doesn’t fit neatly into traditional lending requirements. A private mortgage could potentially provide financing while they work toward a longer-term solution.
But before signing, they should understand the total borrowing cost, repayment requirements, renewal options, and what needs to happen for the next stage of financing.
That last part is easy to overlook.
Getting approved is one milestone. Having a sustainable plan after approval is another.
Questions Worth Asking Before You Sign
If you’re considering alternative mortgage financing, don’t be shy about asking questions.
At minimum, understand:
- What is the total cost of borrowing?
- What fees are charged upfront?
- What is the mortgage term?
- What happens when the term ends?
- Are there renewal conditions?
- What are the prepayment or discharge costs?
- What happens if your financial situation changes?
- What is your realistic exit strategy?
- How does the mortgage affect your other financial goals?
Canada’s consumer guidance also recommends reading mortgage agreements carefully and asking questions about anything you don’t understand.
That’s good advice for any mortgage—not just a private one.
Financing Is Only One Piece of the Puzzle
At Bow Valley Private Wealth Management, the broader conversation can include debt planning, lending and mortgages, investments, retirement, insurance, and other financial priorities.
Because sometimes the mortgage itself isn’t the real problem.
It may be cash flow.
It may be debt structure.
It may be timing.
Or it may simply be that the current financing no longer fits where you’re trying to go.
A mortgage should support your financial direction—not quietly work against it.
Before choosing a Private Mortgage Lender, take a step back and look at the complete picture. Understand the cost, know your obligations, and have a realistic plan for what happens next.
That extra bit of planning can make a big difference.