Sign up with Google
 Sign in with Zoho
Introduction
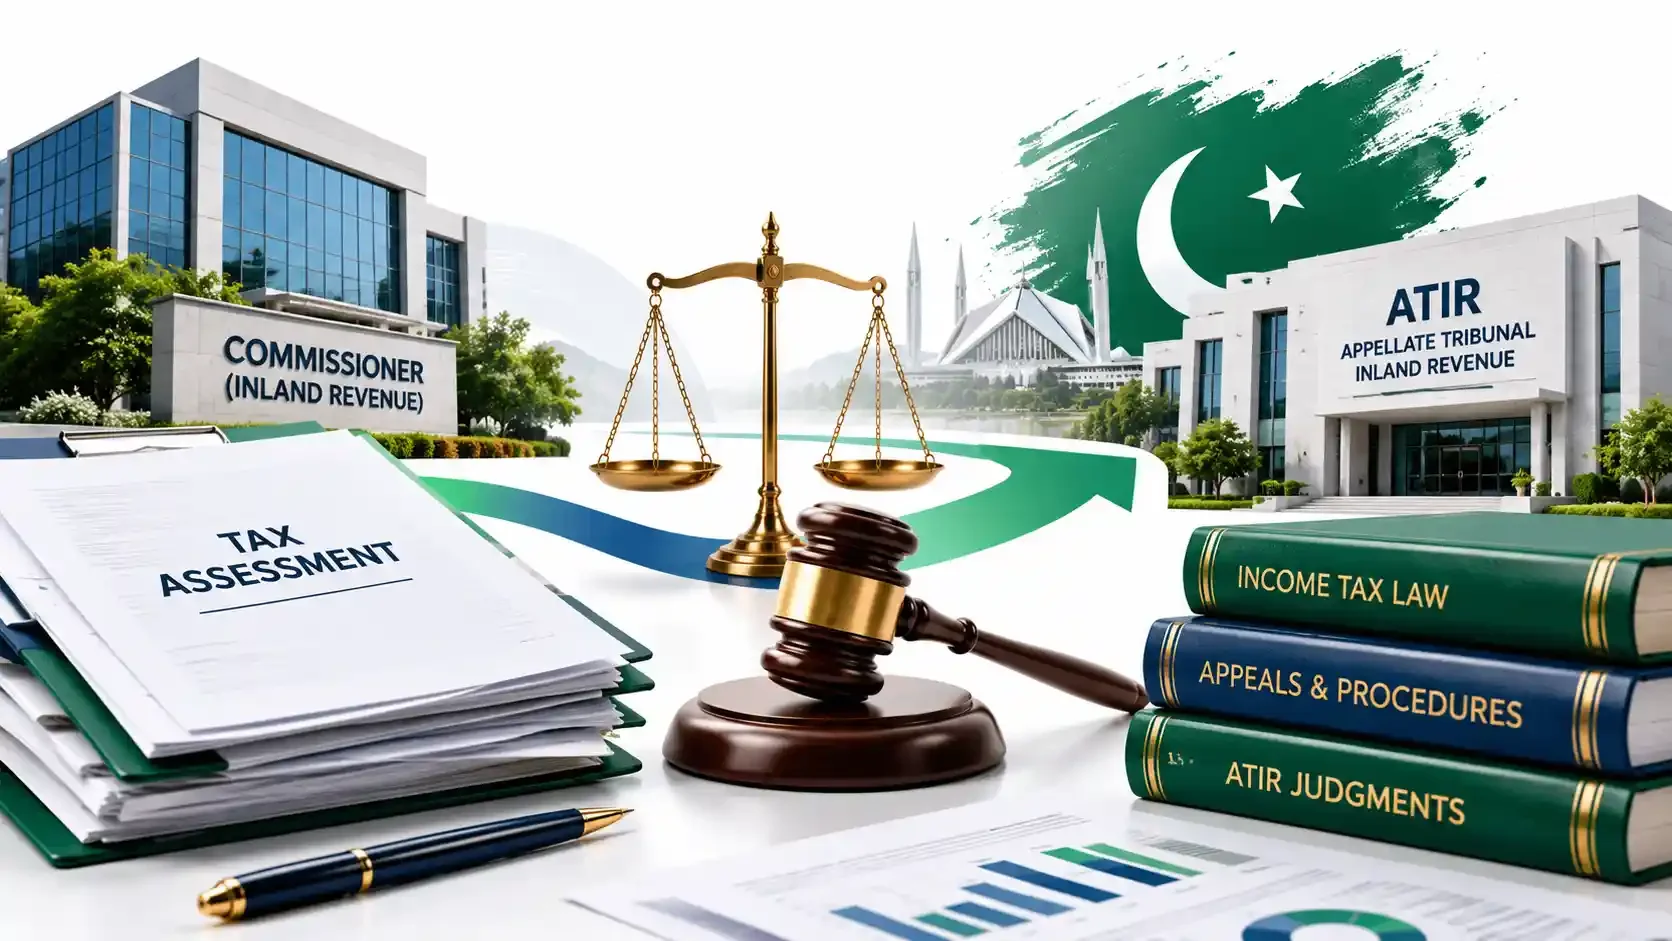
Receiving an assessment order, a penalty order or a refund rejection from the Federal Board of Revenue (FBR) is stressful, but it is rarely the end of the road. Pakistan's tax laws give taxpayers a layered right of appeal, and the taxpayers who use it well are usually the ones who understand the forums, the deadlines and the paperwork before the clock starts running.
The appeal system has also moved quickly. In 2024 the route to the Appellate Tribunal Inland Revenue (ATIR) was reshaped; the Finance Act, 2025 restored a two-tier system and the Finance Act, 2026 added faceless appeals and an internal scrutiny committee for the department's own litigation. If you are working from an article written two years ago, parts of it may now be wrong.
This guide walks you through the full journey: what a tax appeal is, how the Commissioner (Appeals) and ATIR differ, the deadlines, the documents, stay of recovery, and what happens after the Tribunal. It is written for individuals, company owners, accountants and early-career tax practitioners. If you have only received a notice (not yet an order), start with our FBR notices explained guide first.
What Is a Tax Appeal, and What Can You Appeal Against?
A tax appeal is a formal, statutory challenge to a decision made by a tax authority. It is not a letter of complaint, and it is not the same as replying to a notice. You appeal against an order, which is the authority's final decision on a matter, to a higher authority that can confirm, change or cancel it.
Under section 127 of the Ordinance, the orders that can be taken to the Commissioner (Appeals) include orders under sections 120, 121 and 122 (assessments and amended assessments), orders holding a person liable for tax not deducted or collected, refund orders under section 170 and penalty orders under section 182. In practice, the orders taxpayers most often challenge are:
- An amended assessment after an audit (see our FBR audit notice guide).
- A best judgment assessment issued when a taxpayer did not respond or file.
- A penalty for late filing, non-filing or other defaults (see FBR non-filer penalties).
- A withholding tax order against a person who allegedly failed to deduct or deposit tax (see what withholding tax is and how to handle it).
- A refund rejection or short refund (see the IRIS tax refund process).
Notice versus order: why the difference matters
A notice asks you to do something or explain something. An order records a decision. Many notices (for example, a show-cause notice before an amendment) give you the chance to be heard, and a strong reply can prevent an adverse order altogether. Our guides on responding to an FBR notice under section 114 and how FBR audit notices work cover that stage. This article starts where those end: when an order has been passed and you disagree with it.
Visit for more Information :