 Sign up with Google
 Sign in with Zoho
Market Outlook
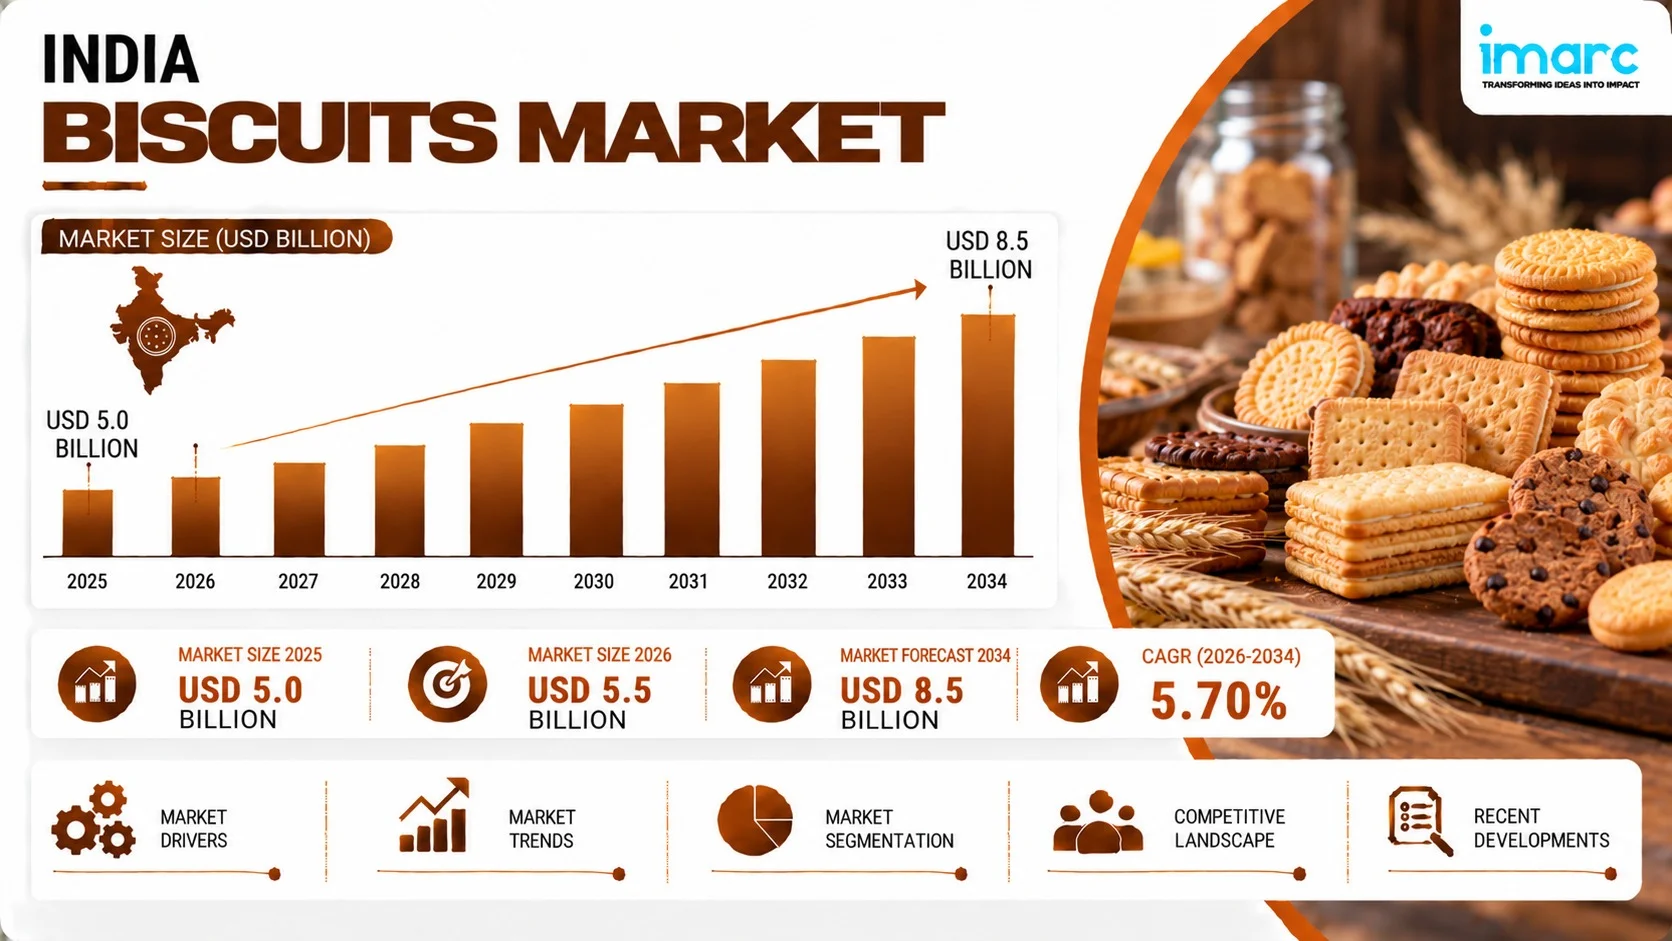
The India biscuits market size increased from USD 5.0 Billion in 2025 to USD 5.5 Billion in 2026. Looking forward, the market is expected to reach USD 8.5 Billion by 2034, exhibiting a growth rate (CAGR) of 5.70% during 2026-2034. The market is growing as a result of rising consumer demand for varied, health-oriented, and convenient snack foods, aided by advances in packaging, ingredients, and distribution channels, to meet changing tastes and busy lifestyles in urban and rural regions.
The Government of India's GST rate rationalisation, reducing biscuit tax from 12% to 5% effective September 2025, has meaningfully improved affordability and is expected to accelerate category formalisation nationwide, collectively expanding the overall India biscuits market share. Health-conscious biscuits made with whole grains, oats and millets are gaining mainstream traction, while premium and indulgence biscuits featuring imported ingredients and upmarket packaging continue attracting consumers willing to pay for luxury treats. The industry demonstrates resilience amid raw material price volatility and intense unorganised sector competition, benefiting from convenient on-the-go packaging formats, growing e-commerce penetration, and the growing footprint of both legacy manufacturers and premium international collaborations.
Market Snapshot:
- Market Size (2025): USD 5.0 Billion
- Market Size (2026): USD 5.5 Billion
- Forecast Market Size (2034): USD 8.5 Billion
- CAGR: 5.70% (2026-2034)
- Product Types Covered: Crackers and Savory Biscuits (Plain Crackers, Flavored Crackers), Sweet Biscuits (Plain Biscuits, Cookies, Sandwich Biscuits, Chocolate-Coated Biscuits, Others)
- Ingredients Covered: Wheat, Oats, Millets, Others
- Packaging Types Covered: Pouches/Packets, Jars, Boxes, Others
- Distribution Channels Covered: Supermarkets and Hypermarkets, Convenience Stores, Independent Bakery, Online Stores, Others
- Regions Covered: North India, South India, East India, West India
What are the Growth Factors of the India Biscuits Market?
- Rapid Urbanisation and Rising Disposable Incomes
India's accelerating urbanisation and rising middle-class disposable incomes are steadily expanding household spending on packaged snack foods, including biscuits, across both metro and non-metro markets. Busy urban lifestyles are normalising biscuits as an everyday convenience food rather than an occasional treat, sustaining structural consumption growth across urban and rural India.
- GST Rate Rationalisation Boosting Affordability
The reduction of GST on biscuits from 12% to 5%, effective September 2025, has meaningfully lowered retail prices, directly boosting affordability and demand across price-sensitive rural and semi-urban segments. This tax relief is expected to accelerate formalisation of the category, benefiting organised players positioned to capture volume shifting away from unbranded local alternatives.
- Growing Preference for Convenient, On-the-Go Snacking
Growing demand for single-serve pouches, resealable packets and travel-friendly formats is reflecting India's increasingly fast-paced urban lifestyles, particularly among working professionals and students on the move. E-commerce platforms are further widening access to a diverse range of packaged biscuit formats, supporting sustained impulse and repeat purchase behaviour across the country.
- Expanding Rural Distribution and Retail Penetration
Leading manufacturers continue expanding distribution networks into rural and remote villages, leveraging decades-long supply chain investments to reach consumers well beyond metropolitan and tier-one markets. This deep rural penetration remains a critical competitive advantage, sustaining volume leadership for established brands across India's vast and geographically dispersed retail landscape across the country.
Request Sample Report – TOC & Key Insights: https://www.imarcgroup.com/india-biscuits-market/requestsample
What Are the Key Trends Shaping the Market?
- Shift Toward Health-Focused Biscuit Formulations
Manufacturers are steadily reformulating traditional biscuit ranges with whole grains, oats, millets and reduced sugar content as health-conscious consumers increasingly scrutinise ingredient labels before purchase. Fortified, gluten-free and digestive biscuit variants are moving from niche health stores into mainstream retail, reshaping the category's overall product mix across urban and rural markets.
- Premiumisation Through International Brand Collaborations
Global biscuit and cookie brands are increasingly partnering with Indian FMCG majors to enter the market through established distribution networks rather than pure import-based models. These collaborations are bringing internationally recognised premium formats to Indian consumers, accelerating category value growth beyond traditional mass-market glucose and cream biscuit segments significantly nationwide.
- Category Diversification into Adjacent Bakery Segments
Established biscuit manufacturers are increasingly diversifying into adjacent bakery categories, including cakes, rusk, croissants and wafers, which are growing at double-digit rates faster than core biscuit lines. This diversification strategy is helping companies capture a larger share of household snacking wallet while reducing dependence on the traditional glucose biscuit segment.
- Growing E-Commerce and Quick-Commerce Category Penetration
Bakery and biscuit adjacency categories are growing nearly three times faster on e-commerce platforms compared to traditional biscuits, reflecting shifting purchase behaviour toward digital-first snack discovery. Quick-commerce apps offering rapid delivery are further accelerating impulse purchase occasions, encouraging manufacturers to develop platform-specific packaging and promotional strategies across India's growing digital grocery market.
Explore the Full Report with Charts, Table of Contents, and List of Figures: https://www.imarcgroup.com/india-biscuits-market
What Are the Major Market Challenges?
- Raw Material Price Volatility Impacting Margins
Fluctuating prices of key inputs including edible oils, wheat, sugar and cocoa continue to squeeze manufacturer margins, creating ongoing cost unpredictability across the biscuit industry. While recent easing in palm oil and cocoa prices has provided some relief, persistently elevated milk prices continue to pressure overall input cost structures for manufacturers nationwide.
- Intense Competition from Unorganised and Regional Players
The biscuit market remains highly competitive, with numerous regional and unorganised manufacturers offering low-cost alternatives that continue holding meaningful market share, particularly in rural and price-sensitive segments. This fragmentation constrains pricing power for organised brands, requiring sustained investment in distribution reach and brand-building to defend market position across the country.
- MRP Adjustment Disruption Following GST Rate Changes
The recent GST rate revision created temporary market disruption as manufacturers adjusted maximum retail prices, with some players retaining odd price points that allowed retailers to capture small-change amounts from unadjusted competitor brands. Restoring pricing consistency across the industry requires coordinated repricing efforts, with full normalisation expected only gradually across subsequent quarters.
How Is the Market Segmented?
- By Product Type: The market is segmented into Crackers and Savory Biscuits (Plain Crackers, Flavored Crackers) and Sweet Biscuits (Plain Biscuits, Cookies, Sandwich Biscuits, Chocolate-Coated Biscuits, Others), with sweet biscuits anchoring overall category volumes across Indian households.
- By Ingredient: The market is segmented into Wheat, Oats, Millets and Others, with wheat-based biscuits dominating consumption, even as oats and millet-based variants gain traction among health-conscious consumers.
- By Packaging Type: The market is segmented into Pouches/Packets, Jars, Boxes and Others, with pouches and packets leading due to their affordability, portability and suitability for both retail and on-the-go consumption.
- By Distribution Channel: The market is segmented into Supermarkets and Hypermarkets, Convenience Stores, Independent Bakery, Online Stores and Others, reflecting the diverse retail formats through which Indian consumers purchase biscuits.
- Regional Insights: The market is segmented into North India, South India, East India and West India, reflecting differing consumption patterns, manufacturing hubs and distribution infrastructure across these regions.
Competitive Landscape:
The India biscuits market is dominated by a small number of large, well-established players alongside a long tail of regional and unorganised manufacturers competing primarily on price. Market leaders maintain their position through extensive rural and urban distribution networks, strong brand recognition built over decades, and continuous product innovation spanning health-focused, premium and adjacent bakery categories. Competitive intensity is increasing as manufacturers diversify into cakes, rusk and wafers while pursuing acquisitions and international brand partnerships to broaden their portfolios and defend market share against both mass-market and premium challengers.
Some of the key players in the market include:
- Britannia Industries Limited
- Parle Products Pvt. Ltd.
- ITC Limited (Sunfeast)
- Surya Food & Agro Ltd. (Priyagold)
- Mondelez India Foods Private Limited
Recent News or Developments
- GST on Biscuits Cut from 12% to 5% (September 2025): The GST Council approved a sweeping two-tier tax restructuring effective September 22, 2025, reducing the rate on biscuits from 12% to 5%, with brokerages including Nomura projecting Britannia, ITC and other major manufacturers as key beneficiaries given the meaningful share of their portfolios falling under the reduced rate.
- Britannia Posts Strong Q3 FY26 Comeback (February 2026): Britannia reported a 17% year-on-year rise in profit to Rs 682 crore and 8.2% sales growth to Rs 4,970 crore, with gross margin expanding 400 basis points on easing palm oil and cocoa costs, alongside new launches including the 50:50 dipped range and Doodh Marie Gold.
- Parle Biscuits Appoints New CEO, Enters Branded Atta Category (September 2026): Parle Biscuits appointed George Kovoor as its Chief Executive Officer effective September 1, 2026, as the company simultaneously announced its entry into the branded Atta category, leveraging the equity of its iconic Parle-G brand to diversify beyond its core biscuits portfolio.
Customization Note: If you require any specific information not covered within this report’s scope, we will provide it as part of the customization.
Frequently Asked Questions (FAQs)
Q1. What is the current size of the India biscuits market?The India biscuits market size increased from USD 5.0 Billion in 2025 to USD 5.5 Billion in 2026.
Q2. What is the expected growth rate of the India biscuits market during 2026-2034?The market is projected to grow at a CAGR of 5.70% during 2026-2034, reaching USD 8.5 Billion by 2034.
Q3. What factors are driving the growth of the India biscuits market?Key growth drivers include rapid urbanisation and rising disposable incomes, GST rate rationalisation boosting affordability, growing preference for convenient, on-the-go snacking, and expanding rural distribution and retail penetration.
Q4. Which segments are covered in the India biscuits market report?The report covers segmentation by product type, ingredient, packaging type, distribution channel and region.
Q5. What are the major challenges facing the India biscuits market?Major challenges include raw material price volatility impacting margins, intense competition from unorganised and regional players, and MRP adjustment disruption following recent GST rate changes.