 Sign up with Google
 Sign in with Zoho
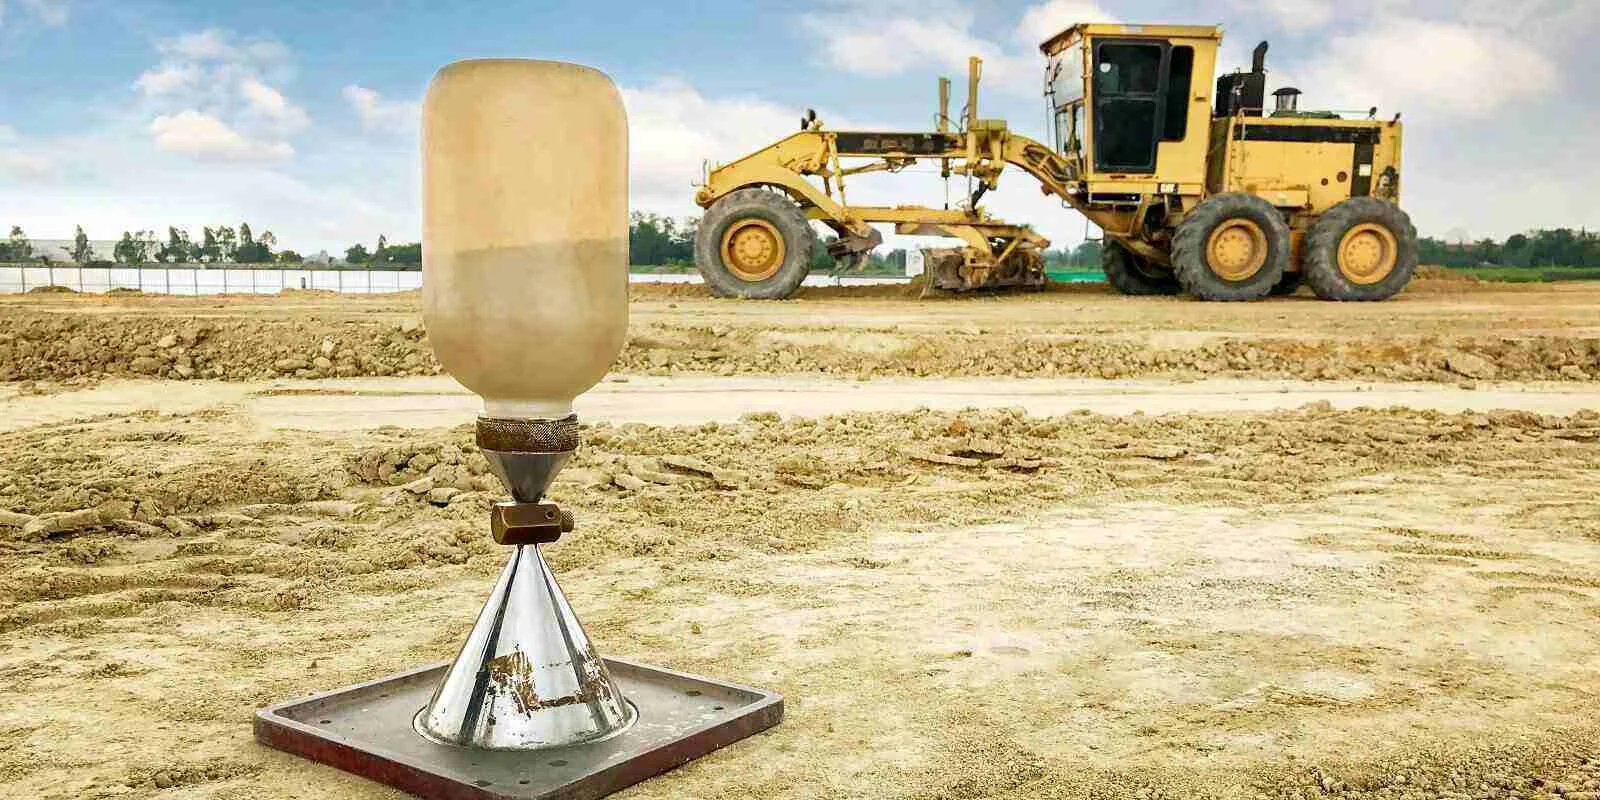
The soil compaction machines market is evolving alongside continued investment in roads, bridges, commercial buildings, industrial facilities, airports, residential developments, and large-scale infrastructure projects. Soil compaction is a critical stage in construction because properly compacted ground provides stability, improves load-bearing capacity, minimizes settlement, and supports the durability of structures and paved surfaces.
Competition in this industry is influenced by equipment performance, operating efficiency, machine durability, technology integration, product portfolios, after-sales service, and pricing. Manufacturers are increasingly focusing on solutions that can deliver consistent compaction while reducing fuel consumption, maintenance requirements, downtime, and operator workload. As construction companies seek greater productivity, equipment suppliers are adapting their offerings to address both conventional construction needs and emerging requirements for connected and environmentally conscious machinery.
Competitive Structure of the Market
The competitive environment includes established construction equipment manufacturers, regional machinery producers, specialized compaction equipment suppliers, and companies offering complementary earthmoving solutions. Participants compete across different machine categories, including single-drum rollers, tandem rollers, pneumatic rollers, vibratory compactors, plate compactors, and other specialized equipment.
Large manufacturers generally benefit from broad distribution networks, established customer relationships, extensive product ranges, and stronger service capabilities. Smaller and regional manufacturers can compete through competitive pricing, customized products, local service support, and faster responses to specific customer requirements.
The soil compaction machines market therefore has a diverse competitive structure rather than relying on a single equipment category or customer group. Contractors may select machinery based on project size, soil conditions, operating environment, available budget, and required productivity.
Product Innovation as a Competitive Factor
Technology is becoming an important area of differentiation among equipment manufacturers. Modern compaction machines increasingly incorporate features designed to improve operating accuracy, productivity, and machine utilization.
Automated compaction measurement systems can help operators monitor ground conditions and machine performance during construction. Intelligent systems can provide information about compaction progress, allowing contractors to identify areas that may require additional passes. Telematics can also provide information related to machine location, operating hours, fuel usage, maintenance schedules, and equipment utilization.
Manufacturers investing in these capabilities can address the growing demand for data-driven construction processes. At the same time, simpler machines remain important in price-sensitive markets where ease of operation, reliability, and straightforward maintenance are major purchasing considerations.
Importance of Product Portfolio
A broad product portfolio gives manufacturers the flexibility to serve different construction applications. Heavy-duty rollers may be suitable for highways and large infrastructure projects, while compact machines can be more practical for urban construction, landscaping, utility work, and confined areas.
Manufacturers are therefore expanding product ranges to cover different operating weights, drum configurations, vibration systems, widths, engine capacities, and machine sizes. Offering multiple configurations enables suppliers to serve contractors with different productivity requirements.
Versatility can also strengthen customer relationships because contractors operating across several project types may prefer suppliers capable of providing multiple equipment solutions. This creates opportunities for manufacturers to compete through complete equipment portfolios rather than individual machines.
After-Sales Service and Dealer Networks
After-sales support is another major element of competition. Construction equipment often operates under demanding conditions, making maintenance, spare parts availability, technical assistance, and repair response important purchasing considerations.
Manufacturers with strong dealer networks can provide customers with easier access to replacement components and service personnel. Preventive maintenance programs can also help contractors reduce unexpected downtime and extend equipment operating life.
Digital service capabilities are becoming increasingly relevant. Remote diagnostics, maintenance alerts, equipment monitoring, and digital service records can help customers manage fleets more effectively. Companies that combine equipment sales with dependable support services can create additional value beyond the initial machine purchase.
Pricing and Ownership Costs
Price remains an important competitive consideration, particularly among small and medium-sized contractors. However, the initial purchase price is only one component of equipment economics. Buyers may also consider fuel consumption, maintenance expenses, parts costs, machine longevity, resale value, productivity, and operator efficiency.
Manufacturers can differentiate themselves by demonstrating favorable total ownership economics. Fuel-efficient engines, durable components, optimized hydraulic systems, and simplified maintenance procedures can potentially reduce operating expenses over the machine's working life.
Flexible financing and leasing arrangements may also influence purchasing decisions. Equipment suppliers that work with dealers and financial partners to offer accessible acquisition options can address customers who may not want to make a large upfront investment.
Regional and Application-Based Competition
Competitive conditions vary by geography because construction activity, regulatory requirements, equipment preferences, and purchasing power differ between markets. Developed construction sectors may place greater emphasis on advanced automation, emissions performance, productivity monitoring, and operator comfort.
Emerging construction markets can present opportunities for manufacturers offering durable and cost-effective equipment suited to infrastructure expansion. Local manufacturing and regional assembly can also help suppliers manage transportation costs and respond more effectively to local demand.
Application-specific requirements further shape competition. Road construction projects may require heavy rollers and high productivity, while building projects can favor compact machines that provide maneuverability in restricted spaces. Agricultural, utility, mining, and industrial applications may create additional demand for specialized compaction solutions.
Sustainability and Efficiency in Competition
Environmental considerations are gradually influencing equipment development. Contractors and project owners are increasingly interested in machinery that can improve productivity while reducing fuel consumption and emissions.
Manufacturers are exploring more efficient powertrains, improved hydraulic systems, optimized vibration technologies, and alternative power solutions. Electric and lower-emission compact equipment may gain attention in applications where operating conditions and charging infrastructure support their use.
Sustainability can also extend beyond the powertrain. Longer machine lifespans, durable components, efficient maintenance, and improved recyclability can contribute to resource efficiency. Companies that incorporate these considerations into product development may strengthen their position as construction customers place greater emphasis on operational sustainability.
Competitive Strategies and Future Direction
Companies competing in the soil compaction machines market are likely to focus on a combination of product innovation, geographic expansion, customer support, and operational efficiency. Partnerships with distributors and construction equipment dealers can help manufacturers strengthen market reach, while investments in digital technologies can create additional service opportunities.
Customization is another potential competitive strategy. Contractors increasingly operate under project-specific conditions, creating demand for equipment configurations suited to particular soil types, working environments, and productivity targets.
Manufacturers may also strengthen their position by investing in operator-focused features. Improved visibility, ergonomic controls, reduced vibration exposure, simplified interfaces, and automated assistance can make machines easier and more comfortable to operate.
Conclusion
Competition in the soil compaction machines market is shaped by more than machine pricing. Equipment reliability, productivity, technology, fuel efficiency, product variety, dealer coverage, maintenance support, and total ownership costs all contribute to purchasing decisions.
As infrastructure development and construction activity continue to create demand for reliable ground preparation equipment, manufacturers are expected to compete through increasingly efficient and technology-enabled solutions. Companies capable of balancing performance, affordability, durability, digital capabilities, and responsive after-sales support can address the diverse requirements of contractors across different applications. The competitive landscape will continue to evolve as equipment users seek higher productivity, lower operating costs, and machinery capable of supporting increasingly modern construction practices.