Sign up with Google
 Sign in with Zoho
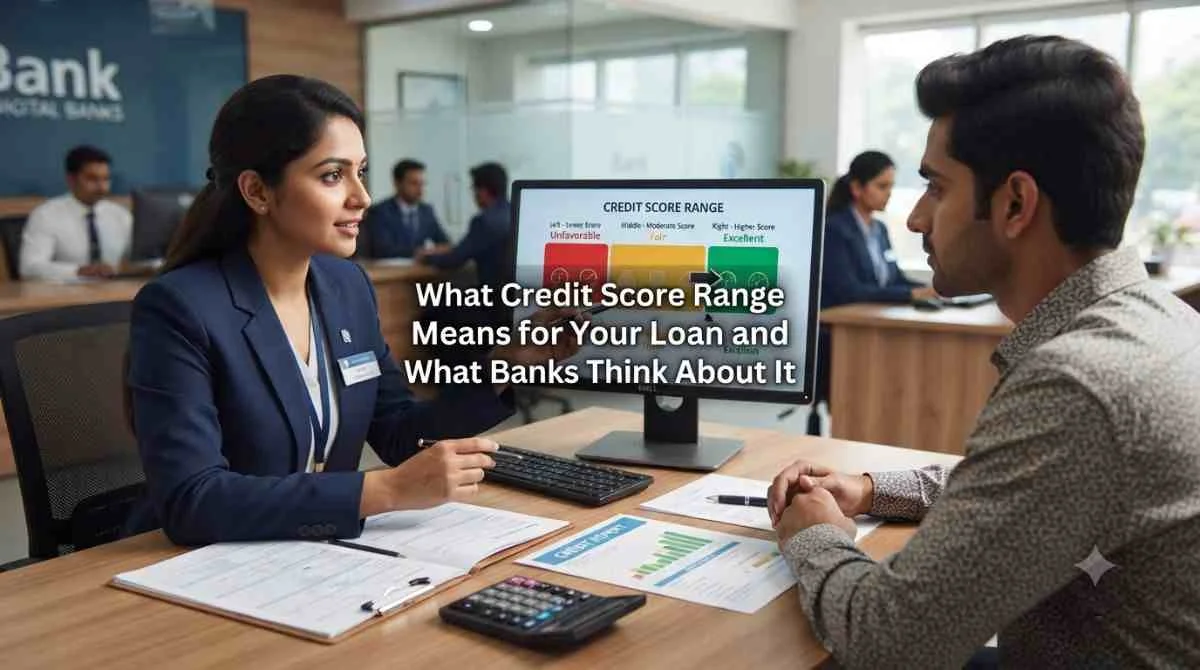
When applying for a loan, it helps to know in advance what sort of conditions and credit score ranges you'll get the best terms and interest rates on a loan. A credit score is a number that indicates your credit worthiness, or how capable you are of repaying borrowed money. This can help lenders decide how likely you are to pay back your loan. In this article, find out what the different credit score ranges are, how having a low credit score affects your loan, and what lenders think.
Understanding the Credit Score Range
Your credit score range can go from 300 to 850, where higher is better and indicates a lower risk to lenders. Here's a quick reminder of typical credit score ranges:
- Poor (300-579): These borrowers encounter an uphill battle when applying for a loan, as lenders view them as high risk.
- You might still be able to borrow money but you will pay a higher-than-average interest rate. You could have a few negative items on your credit reports.
- Good credit scores broaden your loan choices and mean you get better rates on your loans.
- Very Good (740-799): Those with this score tend to be approved for more attractive loans.
- This is the highest score that indicates you are a low-risk borrower and will get the best interest rate and loan terms.
How Credit Scores Affect Loan Eligibility
Your credit score affects whether or not you are approved for a loan and at what interest rate. Learn how different credit score ranges influence the types of loans that are available to you:
Poor Credit Score
A low credit score can restrict borrowing opportunities. Low credit score lenders may be reluctant to lend you money, or they may charge very high-interest rates to offset the risk. Borrowers falling in this range might need to provide collateral or a co-signer for a loan, especially if it is for a large amount, such as a mortgage or auto loan.
Fair Credit Score
Individuals with a good credit score will still be able to obtain personal and auto loans; however, they'll be subject to more requirements and higher loan interest rates. While some lenders may still be willing to lend to this group, it is much safer to be cautious and have fewer options.
Good and Very Good Credit Scores
Those who are within the ranges of good and very good scores tend to have many loan options. Banks tend to see this demographic as more reliable and feel comfortable giving them lower rates. People within the very good range often get extra advantages such as lowered fees and improved loan terms.
Excellent Credit Score
Your outstanding credit score will likely get you the best of the best loan products, including lower interest rates and better repayment terms and lower fees. With so many lenders fighting for your business, your options for loans are plentiful if you have a solid credit history.
What Lenders Look For in a Credit Score Range
Lenders use your credit score as part of their decision-making process. In addition to looking at your score, they also review your entire credit history, including:
Payment history
Payment history makes up a large part of your credit score. All creditors and lenders, including Bajaj Finance, would like to see you have a good record of making payments on time. Missed or late payments, defaults and bankruptcies will lower your score and are warning signs to lenders.
Credit Utilization Ratio
Credit utilization ratio, that is, the percentage of your total available credit you’re using, is also taken into account. A low ratio (30% or less) shows lenders that you use credit wisely.
Length of Credit History
How long your credit history is can also impact your score. A lengthier credit history could give lenders more insight into whether or not you are trustworthy.
Types of Credit
Diverse credit types, including installment loans (like car loans) and revolving credit (like credit cards), can positively impact your credit score. Lenders may prefer borrowers who can successfully manage different types of credit accounts.
Recent Credit Inquiries
Frequent applications for new credit recently can be an indicator of financial distress or increased risk to lenders. By restricting new applications, you will be able to sustain a strong credit profile.
Strategies for Improving a Low Credit Score
If you are in the low end of credit scores there is some good news! There are things you can do to better your credit score:
Check Your Credit Report
First, order a copy of your credit report. Check it to identify any errors or irregularities as even small mistakes can affect your score. If there are issues, take the relevant steps to challenge them.
Consistent Payment Practices
Make payments on time. Set up automatic payments or reminders to pay bills on time to build a positive credit history.
Reduce Outstanding Debt
Focus on reducing current debt, especially high credit card balances. Paying down these debt can help boost your score and show lenders you manage credit responsibly.
Limit Credit Applications
This can also be a damaging application to your credit score, so try to improve your current credit position before applying for anything new.
Financial Counseling
Consider working with a financial advisor or credit counselor. These professionals can provide personalized guidance, helping you develop a strategy to improve your credit score over time.
Conclusion
How To Know The Range Of Credit Score There are many ways you can understand your credit score range. As an example: if your credit score is low, it can be very difficult and expensive to secure loans; knowing the factors that impact your credit profile will help you get the mortgage you want. Improving your credit score needs constant attention.
In the end, no matter where you are at that moment in time, proactive steps can help you towards a higher credit score and greater loan approval potential. Whether you’re in need of a vehicle loan, mortgage or personal loan, raising that credit score can only mean good things!