Sign up with Google
 Sign in with Zoho
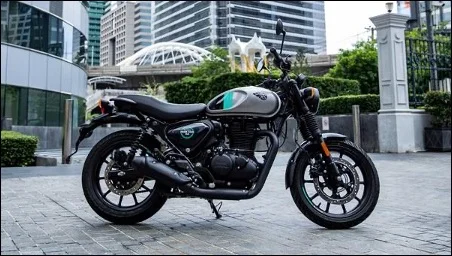
The Royal Enfield Hunter 350 has a compact roadster feel, but its monthly financing cost depends on how much you pay upfront and what terms a lender approves. There is no fixed Hunter 350 EMI for every Indian buyer. A useful estimate starts with a quotation for the precise variant, followed by a realistic loan amount, interest assumption, and repayment period.
Identify the Hunter 350 version you want
The Hunter is part of Royal Enfield's 349 cc single-cylinder family, offering approximately 20.2 bhp and 27 Nm. The Royal Enfield Hunter 350 features compact proportions and a 17-inch wheel layout, distinguishing it from the larger-feeling Bullet and Classic 350. However, Hunter versions can differ in wheel construction, braking configuration, and equipment, so price comparisons must be made at the variant level.
Sit on the motorcycle and test low-speed manoeuvres before committing to a booking. A practical daily choice will influence your spending for years. Check dealer availability, the current ex-showroom quotation and any extra items proposed during purchase.
What determines the down payment?
The lender's approved loan-to-value arrangement and your voluntary initial contribution both influence what you pay at the beginning. You might choose a larger amount to reduce the balance, but the provider can also require a minimum contribution under its policy. Registration, insurance, and optional accessories are not necessarily financed on the same basis as the motorcycle.
Request two separate documents: an itemised dealer quotation and the lender's proposed financing breakdown. Compare them line by line. Money already paid as a refundable booking deposit may be adjusted in the final invoice, but you should verify the dealership's written terms before assuming it becomes part of the down payment.
A Hunter 350 loan illustration
Consider an example that finances Rs. 1,60,000 over 36 months with 12% annual interest calculated on the reducing balance. The corresponding instalment is approximately Rs. 5,314, with total interest of about Rs. 31,314 before charges. These figures demonstrate the calculation and should not be mistaken for an available Hunter 350 finance scheme.
If you increase your initial payment, a smaller financed principal may lower the EMI and total interest. If you select more months instead, the monthly amount can fall while lifetime interest rises. Both choices should be assessed against the final amount paid, rather than considering the EMI in isolation.
Compare a shorter and longer commitment
Shorter tenure means a larger monthly repayment for a given principal and rate, but usually less accumulated interest. Longer tenure leaves more room in the monthly budget at the cost of holding the debt for additional months. This trade-off matters when you also have rent, family commitments or other instalments to meet.
Ask the lender to provide the total payable for two tenures using the same approved principal. Read the schedule for due dates and how missed payments are handled. If you hope to settle early, check whether preclosure or part-payment fees could reduce the benefit.
Factor in daily ownership expenses
The Hunter 350 is often considered for urban riding, where stop-and-go traffic and frequent starts affect real petrol consumption. Service intervals, tyre care, chain adjustment, insurance renewal and parking also influence the annual budget. These expenses do not disappear because the purchase is financed.
Set aside an amount for protective equipment, particularly if the motorcycle will replace public transport or a smaller commuter. A well-fitted helmet, jacket and gloves deserve priority. Ask the service centre about maintenance requirements for the exact variant so you can plan regular costs rather than react to them.
Does the Hunter offer value over other Royal Enfield bikes?
The Hunter can be appealing if you want the Royal Enfield bike's engine character in an urban-friendly package. The Bullet and Classic lean more strongly into classic styling and a substantial stance, while the Meteor takes a cruiser approach. Choosing the Hunter for a shorter everyday route may be sensible, but personal comfort should decide the outcome.
Do not compare only the difference between two starting EMIs. Check the complete price difference between the exact models and the likely cost of insurance, servicing and equipment. A larger deposit might make a higher-priced bike look similarly affordable each month while requiring more cash upfront.
Verify eligibility and charges before accepting
A loan provider can examine income, existing borrowing, repayment history and documents before deciding an offer. The same person may receive different terms from different providers. A dealer's promotional finance example is not a guarantee of final approval at that rate.
Review identity and address requirements, the interest calculation, processing charge, insurance conditions, and repayment frequency. Confirm whether add-on products are optional. Retain copies of the final agreement, payment receipts, and vehicle papers. Clear records make it easier to resolve disputes or close the account later.
Choose a Hunter 350 payment plan you can sustain
Start with a confirmed variant quotation, maintain a sensible cash reserve, and calculate monthly repayments under more than one tenure. Then add the costs of actually using the motorcycle. The right down payment is not simply the smallest available or the largest you can manage today; it is the contribution that makes the whole purchase affordable over time.